Financial modeling with jump processes is a fully explored domain.
We present in this post some of the theoretical aspects of Lévy processes.
We also expose a subset of jump diffusion models available into LexiFi Apropos
Element of stochastic calculus
In this section, we recall some key points on the extension to discontinuous processes (Itô formula, measure theory, … ).
we also present Lévy processes (Lévy-Itô decomposition, Lévy-Khintchine representation, …).
The reader can expand/collapse for more information
Extension to discontinuous processes
Let ( X t ) t ∈ R + (X_t)_{t\in\mathbb{R}^+} ( X t ) t ∈ R + X X X f f f
f ( X t ) = f ( X 0 ) + ∫ 0 t f ′ ( X s ) d X s + 1 2 ∫ 0 t f ′ ′ ( X s ) d [ X ] s f(X_{t}) = f(X_{0}) + \int\limits_{0}^{t} {f'(X_{s}) dX_{s} } + \frac{1}{2} \int\limits_{0}^{t} {f''(X_{s}) d \left[ X \right]_{s} } f ( X t ) = f ( X 0 ) + 0 ∫ t f ′ ( X s ) d X s + 2 1 0 ∫ t f ′′ ( X s ) d [ X ] s Generalised Itô formula:
Let X X X
f ( X t ) = f ( X 0 ) + ∫ 0 t f ′ ( X s − ) d X s + 1 2 ∫ 0 t f ′ ′ ( X s − ) d [ X ] s + ∑ s ≤ t [ △ f ( X s ) − f ′ ( X s − ) △ X s − − 1 2 f ′ ′ ( X s − ) △ X s 2 ]
\begin{align*}
f(X_{t}) = f(X_{0}) & + \displaystyle \int\limits_{0}^{t} {f'(X_{s^{-}}) dX_{s} } +
\frac{1}{2} \int\limits_{0}^{t} {f''(X_{s^-}) d \left[ X \right]_{s} } \\
& + \displaystyle \sum_{s \le t} {\left[ \triangle f(X_{s}) - f'(X_{s^{-}}) \triangle X_{s^{-}} - \frac{1}{2} f''(X_{s^-}) \triangle X_{s}^{2} \right]}
\end{align*}
f ( X t ) = f ( X 0 ) + 0 ∫ t f ′ ( X s − ) d X s + 2 1 0 ∫ t f ′′ ( X s − ) d [ X ] s + s ≤ t ∑ [ △ f ( X s ) − f ′ ( X s − ) △ X s − − 2 1 f ′′ ( X s − ) △ X s 2 ]
with
X t − = lim s → t s < t X s X_{t^{-}} = \displaystyle \lim_{s \to t \atop s < t} X_s X t − = s < t s → t lim X s △ X t = X t − X t − \triangle X_t = X_t - X_{t^{-}} △ X t = X t − X t − ∑ s ≤ t △ X s = ∑ { t i , 0 ≤ t i ≤ t a n d △ X t i ≠ 0 } △ X t i \displaystyle \sum_{s \le t} \triangle X_s = \displaystyle \sum_{ \{ t_i , 0 \le t_i \le t \;\; and \;\; \triangle X_{t_i} \neq 0 \} } \triangle X_{t_i} s ≤ t ∑ △ X s = { t i , 0 ≤ t i ≤ t an d △ X t i = 0 } ∑ △ X t i { t i , 0 ≤ t i ≤ t \{ t_i , 0 \le t_i \le t { t i , 0 ≤ t i ≤ t △ X t i ≠ 0 } \triangle X_{t_i} \neq 0 \} △ X t i = 0 }
Splitting: continuous/discontinuous processes
Decomposition (continuous and discontinuous):
X = X c ⏟ c o n t i n u o u s p a r t + X d ⏟ d i s c o n t i n u o u s p a r t = X c + ∑ s ≤ . △ X s X = \underbrace{X^{c}}_{continuous \; part} + \underbrace{X^{d}}_{discontinuous \; part} = X^{c} + \displaystyle \sum_{s \le .} \triangle X_{s} X = co n t in u o u s p a r t X c + d i sco n t in u o u s p a r t X d = X c + s ≤ . ∑ △ X s The quadratic covariation between two processes is defined by:
[ X , Y ] t = lim ∣ σ n ∣ → 0 ∑ i = 1 n ( X t i − X t i − 1 ) ( Y t i − Y t i − 1 ) \left[ X,Y \right]_{t} = \displaystyle \lim_{ \left| \sigma_{n} \right| \to 0} \sum_{i=1}^{n} (X_{t_i} - X_{t_{i-1}}) (Y_{t_i} - Y_{t_{i-1}}) [ X , Y ] t = ∣ σ n ∣ → 0 lim i = 1 ∑ n ( X t i − X t i − 1 ) ( Y t i − Y t i − 1 )
with ∣ σ n ∣ = sup { t i − t i − 1 ∀ i ∈ 1 , … , n } \left| \sigma_{n} \right| = \sup \{ t_i -t_{i-1} \forall i \in 1,\ldots ,n \} ∣ σ n ∣ = sup { t i − t i − 1 ∀ i ∈ 1 , … , n } σ n = { t 0 = 0 < … < t n = t } \sigma_n = \{ t_0 = 0 < \ldots < t_n = t \} σ n = { t 0 = 0 < … < t n = t } [ 0 ; t ] [ 0 ; t ] [ 0 ; t ]
We expose two interesting features:
[ X , Y ] t c = [ X , Y ] t − ∑ s ≤ t △ X s △ Y s = [ X c , Y c ] t [X,Y]_{t}^{c} = [X,Y]_{t} - \displaystyle \sum_{s \le t} \triangle X_{s} \triangle Y_{s} = [X^{c},Y^{c}]_{t} [ X , Y ] t c = [ X , Y ] t − s ≤ t ∑ △ X s △ Y s = [ X c , Y c ] t d X t = d X t c + △ X t d X_t = d X_t^c + \triangle X_t d X t = d X t c + △ X t
Lévy process
Definition
Let X X X X X X
X 0 = 0 X_0 = 0 X 0 = 0 X X X X X X
Two important features are:
X X X ∀ ϵ ∈ R + , lim s → 0 P ( ∣ X s + t − X t ∣ > ϵ ) = 0 \forall \epsilon \in \mathbb{R}^{+}, \displaystyle \lim_{s \rightarrow 0} \mathbb{P} ( |X_{s+t} - X_t| > \epsilon ) = 0 ∀ ϵ ∈ R + , s → 0 lim P ( ∣ X s + t − X t ∣ > ϵ ) = 0 X X X ∀ t ∈ R + , P ( X t − = X t ) = 1 \forall t \in \mathbb{R}^+, \mathbb{P} (X_{t^-} = X_t) = 1 ∀ t ∈ R + , P ( X t − = X t ) = 1
Remark: If X X X X t = γ t + A W t X_t = \gamma t + A W_t X t = γ t + A W t γ ∈ R d \gamma \in \mathbb{R}^d γ ∈ R d W W W A A A
Probability measure
Let ( Ω , P , F ) (\Omega, P, \mathcal{F}) ( Ω , P , F ) ( E , ε ) (E, \varepsilon) ( E , ε )
Random measure:
M M M Ω × ε → R \Omega \times \varepsilon \rightarrow \mathbb{R} Ω × ε → R
∀ ω ∈ Ω \forall \omega \in \Omega ∀ ω ∈ Ω M ( ω , ⋅ ) M(\omega,\cdot) M ( ω , ⋅ ) ε \varepsilon ε ∀ A ∈ ε \forall A \in \varepsilon ∀ A ∈ ε M ( ⋅ , A ) M(\cdot,A) M ( ⋅ , A )
Poisson random measure:
Let μ \mu μ ( E , ε ) (E, \varepsilon) ( E , ε ) M M M Ω × ε → R \Omega \times \varepsilon \rightarrow \mathbb{R} Ω × ε → R μ \mu μ
∀ A ∈ ε \forall A \in \varepsilon ∀ A ∈ ε μ ( A ) < + ∞ \mu(A) < +\infty μ ( A ) < + ∞ M ( ⋅ , A ) M(\cdot,A) M ( ⋅ , A ) μ ( A ) \mu(A) μ ( A ) ( = E [ M ( ⋅ , A ) ] ) ( \, = E[M(\cdot,A)] \,\,) ( = E [ M ( ⋅ , A )] ) ∀ ( A 1 , … , A n ) ∈ ϵ n \forall (A_1, \ldots, A_n) \in \epsilon^n ∀ ( A 1 , … , A n ) ∈ ϵ n M ( ⋅ , A 1 ) , … , M ( ⋅ , A n ) M(\cdot,A_1), \ldots, M(\cdot,A_n) M ( ⋅ , A 1 ) , … , M ( ⋅ , A n )
Jump measure:
Let X be a cadlag process with value in R d \mathbb{R}^d R d X X X [ 0 ; ∞ ) × R d [0;\infty) \times \mathbb{R}^d [ 0 ; ∞ ) × R d
∀ A ∈ ( R + × R d ) , J X ( A ) = # { t : Δ X t ≠ 0 and ( t , Δ X t ) ∈ A } \forall A \in ( \mathbb{R}^+ \times \mathbb{R}^d),\quad J_X(A) = \# \{t:\Delta X_t \neq 0 \text{ and } (t,\Delta X_t) \in A \} ∀ A ∈ ( R + × R d ) , J X ( A ) = # { t : Δ X t = 0 and ( t , Δ X t ) ∈ A } Property: A jump measure of a Lévy process is a Poisson measure.
Remark: A jump measure of the set ( [ t 1 , t 2 ] , B ) ([t1,t2],B) ([ t 1 , t 2 ] , B ) t 1 t1 t 1 t 2 t2 t 2 B B B
Lévy measure:
Let X X X R d \mathbb{R}^d R d X X X
∀ A ∈ B ( R d ) , ν ( A ) = E [ # { t ∈ [ 0 , 1 ] : Δ X t ≠ 0 and Δ X t ∈ A } ] \forall A \in \mathcal{B} (\mathbb{R}^d),\quad \nu(A) = \mathbb{E}[ \# \{ t \in [0,1]: \Delta X_t \neq 0 \text{ and }\Delta X_t \in A \} ] ∀ A ∈ B ( R d ) , ν ( A ) = E [ # { t ∈ [ 0 , 1 ] : Δ X t = 0 and Δ X t ∈ A }] Lévy-Itô decomposition
Let X X X R d \mathbb{R}^d R d ν \nu ν
Its jump measure J X J_X J X [ 0 ; ∞ ) [0;\infty) [ 0 ; ∞ ) d t × ν dt \times \nu d t × ν
Its Lévy measure verifies ∫ R d ( ∥ x ∥ 2 ) ∧ 1 ) ν ( d x ) < ∞ \displaystyle \int\limits_{\mathbb{R}^d} (\|x\|^2)\wedge 1) \nu(dx) < \infty R d ∫ ( ∥ x ∥ 2 ) ∧ 1 ) ν ( d x ) < ∞
There exists γ ∈ R d \gamma \in \mathbb{R}^d γ ∈ R d B B B A A A X t = γ t + B t + N t + M t N t = ∫ ∣ x ∣ > 1 , s ∈ [ 0 , t ] x J X ( d s × d x ) M t = ∫ 0 < ∣ x ∣ < 1 , s ∈ [ 0 , t ] x J ~ X ( d s × d x ) = ∫ 0 < ∣ x ∣ < 1 , s ∈ [ 0 , t ] x [ J X ( d s × d x ) − ν ( d x ) d s ]
\begin{align*}
X_t = & \gamma t + B_t + N_t + M_t \\
N_t = & \displaystyle \int\limits_{ |x| > 1, s \in [0,t] } x J_X(ds \times dx) \\
M_t = & \displaystyle \int\limits_{ 0 < |x| < 1, s \in [0,t] } x \tilde{J}_X(ds \times dx)
= \displaystyle \int\limits_{ 0 < |x| < 1, s \in [0,t] } x [J_X(ds \times dx) - \nu(dx)ds]
\end{align*}
X t = N t = M t = γ t + B t + N t + M t ∣ x ∣ > 1 , s ∈ [ 0 , t ] ∫ x J X ( d s × d x ) 0 < ∣ x ∣ < 1 , s ∈ [ 0 , t ] ∫ x J ~ X ( d s × d x ) = 0 < ∣ x ∣ < 1 , s ∈ [ 0 , t ] ∫ x [ J X ( d s × d x ) − ν ( d x ) d s ]
The process N N N
The process M M M
We remove the mean of small jumps so that the integral will be computable (can be infinite).
Let’s note that M M M
We only have to define a Lévy process using the following tuple: ( A , ν , γ ) (A, \nu, \gamma) ( A , ν , γ )
Remark:
We find the commonly used formula for X X X ( A , 0 , γ ) (A, 0, \gamma ) ( A , 0 , γ ) ϵ ∈ R \epsilon \in \mathbb{R} ϵ ∈ R
N t = ∫ ∣ x ∣ > ϵ , s ∈ [ 0 , t ] x J X ( d s × d x ) M t = ∫ 0 < ∣ x ∣ < ϵ , s ∈ [ 0 , t ] x J ~ X ( d s × d x ) = ∫ 0 < ∣ x ∣ < ϵ , s ∈ [ 0 , t ] x [ J X ( d s × d x ) − ν ( d x ) d s ] γ ϵ = γ − ∫ ϵ < ∣ x ∣ < 1 , s ∈ [ 0 , t ] x ν ( d x ) d s
\begin{align*}
N_t = & \displaystyle \int\limits_{ |x| > \epsilon, s \in [0,t] } x J_X(ds \times dx) \\
M_t = & \displaystyle \int\limits_{ 0 < |x| < \epsilon, s \in [0,t] } x \tilde{J}_X(ds \times dx)
= \displaystyle \int\limits_{ 0 < |x| < \epsilon, s \in [0,t] } x [J_X(ds \times dx) - \nu(dx)ds] \\
\gamma^\epsilon = & \gamma - \displaystyle \int\limits_{ \epsilon < |x| < 1, s \in [0,t] } x \nu(dx)ds
\end{align*}
N t = M t = γ ϵ = ∣ x ∣ > ϵ , s ∈ [ 0 , t ] ∫ x J X ( d s × d x ) 0 < ∣ x ∣ < ϵ , s ∈ [ 0 , t ] ∫ x J ~ X ( d s × d x ) = 0 < ∣ x ∣ < ϵ , s ∈ [ 0 , t ] ∫ x [ J X ( d s × d x ) − ν ( d x ) d s ] γ − ϵ < ∣ x ∣ < 1 , s ∈ [ 0 , t ] ∫ xν ( d x ) d s We can compute the lim ϵ → 0 \displaystyle \lim_{\epsilon \rightarrow 0} ϵ → 0 lim
Lévy-Khintchine representation
Let X X X ( A , ν , γ ) (A, \nu, \gamma) ( A , ν , γ )
E [ e i u X t ] = e x p { t [ i γ u − A u 2 2 + ∫ R ( e i u x − 1 − i u x 1 ∣ x ∣ ≤ 1 ) ν ( d x ) ] }
\mathbb{E} [ e^{iuX_t} ] = exp \left\{\, t \, \big[\, i\, \gamma\, u - \frac{A u^2}{2} +
\displaystyle \int\limits_{\mathbb{R}} ( e^{i \, u \, x} - 1 - i \, u \, x 1_{|x| \le 1} ) \nu (dx) \,\big]\, \right\}
E [ e i u X t ] = e x p ⎩ ⎨ ⎧ t [ i γ u − 2 A u 2 + R ∫ ( e i u x − 1 − i u x 1 ∣ x ∣ ≤ 1 ) ν ( d x ) ] ⎭ ⎬ ⎫ Let M be a Poisson random measure on ( E , ε ) (E, \varepsilon) ( E , ε ) μ \mu μ B ∈ ε B \in \varepsilon B ∈ ε ∫ B ∣ e f ( x ) − 1 ∣ μ ( d x ) < ∞ \displaystyle \int\limits_{B} |e^{f(x)} - 1| \mu(dx) < \infty B ∫ ∣ e f ( x ) − 1∣ μ ( d x ) < ∞
E [ e ∫ B f ( x ) M ( d x ) ] = e x p [ ∫ B ( e f ( x ) − 1 ) μ ( d x ) ] \mathbb{E} \left[e^{ \, \int\limits_{B} f(x) M(dx) \,}\right] = exp \left[ \, \int\limits_{B} ( e^{f(x)} - 1 ) \mu(dx)\,\right] E [ e B ∫ f ( x ) M ( d x ) ] = e x p B ∫ ( e f ( x ) − 1 ) μ ( d x ) Exponential Lévy process
Let X X X ( σ , ν , γ ) (\sigma, \nu, \gamma) ( σ , ν , γ ) Y = e X Y = e^{X} Y = e X
Y t = e X 0 + ∫ 0 t e X s − d X s + 1 2 ∫ 0 t e X s − d [ X s ] + ∑ s ≤ t [ Δ e X s − e X s − Δ X s ] = 1 + ∫ 0 t Y s − d X s + 1 2 ∫ 0 t Y s − σ 2 d s + ∑ s ≤ t [ e X s − + Δ X s − e X s − − e X s − Δ X s ] = 1 + ∫ 0 t Y s − d X s + 1 2 ∫ 0 t Y s − σ 2 d s + ∑ s ≤ t Y s − [ e Δ X s − 1 − Δ X s ] = 1 + ∫ 0 t Y s − d X s + 1 2 ∫ 0 t Y s − σ 2 d s + ∫ 0 t ∫ R Y s − [ e x − 1 − x ] J X ( d s × d x ) Y t = 1 + ∫ 0 t Y s − [ γ + σ 2 2 ] d s + ∫ 0 t Y s − σ d W s + ∫ 0 t Y s − ∫ R x J X ( d s × d x ) − ∫ 0 t Y s − ∫ − 1 1 x ν ( d x ) d s + ∫ 0 t ∫ R [ Y s − [ e x − 1 − x ] J X ( d s × d x )
\begin{align*}
Y_t = & e^{X_0} + \int\limits_0^t e^{X_{s^-}} d X_s + \frac{1}{2} \int\limits_0^t e^{X_{s^-}} d [X_s] + \displaystyle \sum\limits_{s \le t} [ \Delta e^{X_s} - e^{X_{s^-}}\Delta {X_s} \, ] \\
= & 1 + \int\limits_0^t Y_{s^-} dX_s + \frac{1}{2} \int\limits_0^t Y_{s^-} \sigma^2 ds + \displaystyle \sum\limits_{s \le t} [ e^{X_{s^-} + \Delta X_s} - e^{X_{s^-}} - e^{X_{s^-}} \Delta X_s ] \\
= & 1 + \int\limits_0^t Y_{s^-} dX_s + \frac{1}{2} \int\limits_0^t Y_{s^-} \sigma^2 ds + \displaystyle \sum\limits_{s \le t} Y_{s^-} [ e^{\Delta X_s} - 1 - \Delta X_s ] \\
= & 1 + \int\limits_0^t Y_{s^-} dX_s + \frac{1}{2} \int\limits_0^t Y_{s^-} \sigma^2 ds + \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1 - x ] J_X (ds \times dx) \\
Y_t = & 1 + \int\limits_0^t Y_{s^-} [ \gamma + \frac{\sigma^2}{2}] ds + \int\limits_0^t Y_{s^-} \sigma dW_s \\
& + \int\limits_0^t Y_{s^-} \int\limits_{\mathbb{R}} x J_X (ds \times dx) - \int\limits_0^t Y_{s^-} \int\limits_{-1}^{1} x \nu (dx) ds \\
& + \int\limits_0^t \int\limits_{\mathbb{R}} [ Y_{s^-} [ e^{x} - 1 - x ] J_X (ds \times dx)
\end{align*}
Y t = = = = Y t = e X 0 + 0 ∫ t e X s − d X s + 2 1 0 ∫ t e X s − d [ X s ] + s ≤ t ∑ [ Δ e X s − e X s − Δ X s ] 1 + 0 ∫ t Y s − d X s + 2 1 0 ∫ t Y s − σ 2 d s + s ≤ t ∑ [ e X s − + Δ X s − e X s − − e X s − Δ X s ] 1 + 0 ∫ t Y s − d X s + 2 1 0 ∫ t Y s − σ 2 d s + s ≤ t ∑ Y s − [ e Δ X s − 1 − Δ X s ] 1 + 0 ∫ t Y s − d X s + 2 1 0 ∫ t Y s − σ 2 d s + 0 ∫ t R ∫ Y s − [ e x − 1 − x ] J X ( d s × d x ) 1 + 0 ∫ t Y s − [ γ + 2 σ 2 ] d s + 0 ∫ t Y s − σ d W s + 0 ∫ t Y s − R ∫ x J X ( d s × d x ) − 0 ∫ t Y s − − 1 ∫ 1 xν ( d x ) d s + 0 ∫ t R ∫ [ Y s − [ e x − 1 − x ] J X ( d s × d x ) We can split the process in a martingale part and a finite variation part. We have:
Y t = 1 + ∫ 0 t Y s − [ γ + σ 2 2 ] d s + ∫ 0 t Y s − σ d W s − ∫ 0 t Y s − ∫ − 1 1 x ν ( d x ) d s + ∫ 0 t ∫ R Y s − [ e x − 1 ] J X ( d s × d x ) + ∫ 0 t ∫ R Y s − [ e x − 1 ] ν ( d x ) d s − ∫ 0 t ∫ R Y s − [ e x − 1 ] ν ( d x ) d s Y t = 1 + ∫ 0 t Y s − [ γ + σ 2 2 ] d s + ∫ 0 t Y s − σ d W s − ∫ 0 t Y s − ∫ − 1 1 x ν ( d x ) d s + ∫ 0 t ∫ R Y s − [ e x − 1 ] J ~ X ( d s × d x ) + ∫ 0 t ∫ R Y s − [ e x − 1 ] ν ( d x ) d s Y t = 1 + ∫ 0 t Y s − [ γ + σ 2 2 ] d s + ∫ 0 t Y s − σ d W s + ∫ 0 t ∫ R Y s − [ e x − 1 ] J ~ X ( d s × d x ) + ∫ 0 t ∫ R Y s − [ e x − 1 − x 1 ∣ x ∣ < 1 ] ν ( d x ) d s
\begin{align*}
Y_t = & 1 + \int\limits_0^t Y_{s^-} [ \gamma + \frac{\sigma^2}{2}] ds + \int\limits_0^t Y_{s^-} \sigma dW_s - \int\limits_0^t Y_{s^-} \int\limits_{-1}^{1} x \nu (dx) ds \\
& + \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1] J_X (ds \times dx) + \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1] \nu (dx) ds - \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1] \nu (dx) ds \\
Y_t = & 1 + \int\limits_0^t Y_{s^-} [ \gamma + \frac{\sigma^2}{2}] ds + \int\limits_0^t Y_{s^-} \sigma dW_s - \int\limits_0^t Y_{s^-} \int\limits_{-1}^{1} x \nu (dx) ds \\
& + \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1 ] \tilde{J}_X (ds \times dx) + \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1] \nu (dx) ds \\
Y_t = & 1 + \int\limits_0^t Y_{s^-} [ \gamma + \frac{\sigma^2}{2}] ds + \int\limits_0^t Y_{s^-} \sigma dW_s \\
& + \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1 ] \tilde{J}_X (ds \times dx) + \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1 - x 1_{|x| < 1}] \nu (dx) ds
\end{align*}
Y t = Y t = Y t = 1 + 0 ∫ t Y s − [ γ + 2 σ 2 ] d s + 0 ∫ t Y s − σ d W s − 0 ∫ t Y s − − 1 ∫ 1 xν ( d x ) d s + 0 ∫ t R ∫ Y s − [ e x − 1 ] J X ( d s × d x ) + 0 ∫ t R ∫ Y s − [ e x − 1 ] ν ( d x ) d s − 0 ∫ t R ∫ Y s − [ e x − 1 ] ν ( d x ) d s 1 + 0 ∫ t Y s − [ γ + 2 σ 2 ] d s + 0 ∫ t Y s − σ d W s − 0 ∫ t Y s − − 1 ∫ 1 xν ( d x ) d s + 0 ∫ t R ∫ Y s − [ e x − 1 ] J ~ X ( d s × d x ) + 0 ∫ t R ∫ Y s − [ e x − 1 ] ν ( d x ) d s 1 + 0 ∫ t Y s − [ γ + 2 σ 2 ] d s + 0 ∫ t Y s − σ d W s + 0 ∫ t R ∫ Y s − [ e x − 1 ] J ~ X ( d s × d x ) + 0 ∫ t R ∫ Y s − [ e x − 1 − x 1 ∣ x ∣ < 1 ] ν ( d x ) d s We therefore have Y = e X = A + M Y = e^{X} = A + M Y = e X = A + M A A A M M M
∀ t ∈ R + , A t = ∫ 0 t Y s − [ γ + σ 2 2 ] d s + ∫ 0 t ∫ R [ e x − 1 − x 1 ∣ x ∣ < 1 ] ν ( d x ) ] d s ∀ t ∈ R + , M t = 1 + ∫ 0 t Y s − σ d W s + ∫ 0 t ∫ R Y s − [ e x − 1 ] J ~ X ( d s × d x )
\begin{align*}
\forall t \in \mathbb{R}^+, A_t = & \int\limits_0^t Y_{s^-} [ \gamma + \frac{\sigma^2}{2} ] ds
+ \int\limits_0^t \int\limits_{\mathbb{R}} [ e^{x} - 1 - x 1_{|x| < 1}] \nu (dx) ] ds \\
\forall t \in \mathbb{R}^+, M_t = & 1 + \int\limits_0^t Y_{s^-} \sigma dW_s
+ \int\limits_0^t \int\limits_{\mathbb{R}} Y_{s^-} [ e^{x} - 1 ] \tilde{J}_X (ds \times dx)
\end{align*}
∀ t ∈ R + , A t = ∀ t ∈ R + , M t = 0 ∫ t Y s − [ γ + 2 σ 2 ] d s + 0 ∫ t R ∫ [ e x − 1 − x 1 ∣ x ∣ < 1 ] ν ( d x )] d s 1 + 0 ∫ t Y s − σ d W s + 0 ∫ t R ∫ Y s − [ e x − 1 ] J ~ X ( d s × d x ) Generality on exponential Lévy models
We develop in this section a general dynamic for exp-Lévy models.
We expose a valuation method using partial integro-differential equation (PIDE).
The reader can expand/collapse for more information.
Underlying dynamic
Let S t S_t S t
∀ t ∈ R , S t = e r t + X t \forall t \in \mathbb{R}, S_t = e^{rt + X_t} ∀ t ∈ R , S t = e r t + X t with X t X_t X t ( σ , ν , γ ) (\sigma, \nu, \gamma) ( σ , ν , γ )
Let’s note ∀ t ∈ R + \forall t \in \mathbb{R}^+ ∀ t ∈ R + C ( t ) = e ∫ 0 t r ( s ) d s C(t) = e^{ \int\limits_0^t r(s)ds } C ( t ) = e 0 ∫ t r ( s ) d s ⇔ \Leftrightarrow ⇔ d C ( t ) C ( t − ) = r d t \frac{d C(t)}{C(t^-)} = r dt C ( t − ) d C ( t ) = r d t ⇔ \Leftrightarrow ⇔ C ( t ) = ∫ 0 t r C ( s − ) d s C(t) = \int\limits_0^t r C(s^{-}) ds C ( t ) = 0 ∫ t r C ( s − ) d s
We have
∀ t ∈ R , S ~ t = S t C t = e X t = A t + M t \forall t \in \mathbb{R}, \tilde{S}_t = \frac{S_t}{C_t} = e^{X_t} = A_t + M_t ∀ t ∈ R , S ~ t = C t S t = e X t = A t + M t
with A t A_t A t M t M_t M t
Under the risk neutral probability, the actualized future price must be a martingale. We can write:
d S ~ t = d ( A t + M t ) = d A t + d M t d\tilde{S}_t = d( A_t + M_t ) = dA_t + dM_t d S ~ t = d ( A t + M t ) = d A t + d M t Therefore, we must have d A t = 0 dA_t = 0 d A t = 0
γ + σ 2 2 + ∫ R [ e x − 1 − x 1 ∣ x ∣ < 1 ] ν ( d x ) = 0 \gamma + \frac{\sigma^2}{2} + \displaystyle \int\limits_{\mathbb{R}} [ e^{x} - 1 - x 1_{|x| < 1}] \nu (dx) = 0 γ + 2 σ 2 + R ∫ [ e x − 1 − x 1 ∣ x ∣ < 1 ] ν ( d x ) = 0 The dynamic of the actualized underlying is:
d S ~ t = d M t = S t − [ σ d W t + ∫ R [ e x − 1 ] J ~ X ( d t × d x ) ] d\tilde{S}_t = dM_t =S_{t^-} \, [ \, \sigma d W_t + \int\limits_{\mathbb{R}} [ e^{x} - 1 ] \tilde{J}_X (dt \times dx) \, ] d S ~ t = d M t = S t − [ σ d W t + R ∫ [ e x − 1 ] J ~ X ( d t × d x ) ] The dynamic is:
d S t S t − = r d t + σ d W t + ∫ R ( e x − 1 ) J ~ X ( d t × d x ) \frac{dS_t}{S_t^-} = r dt + \sigma dW_t + \int\limits_{\mathbb{R}} (e^x - 1) \tilde{J}_X (dt \times dx) S t − d S t = r d t + σ d W t + R ∫ ( e x − 1 ) J ~ X ( d t × d x ) with
r , σ ∈ R 2 r, \sigma \in \mathbb{R}^2 r , σ ∈ R 2 J ~ X ( d s × d x ) = J X ( d s × d x ) − ν ( d x ) d s \tilde{J}_X (ds \times dx) = J_X (ds \times dx) - \nu(dx) ds J ~ X ( d s × d x ) = J X ( d s × d x ) − ν ( d x ) d s ν \nu ν X X X J X J_X J X R + \mathbb{R}^+ R + d t × ν dt \times \nu d t × ν
Partial integro-differential equation
Let’s note ∀ t ∈ R , V ( t , S t ) \forall t \in \mathbb{R}, V(t,S_t) ∀ t ∈ R , V ( t , S t )
To find the partial integro-differential equation, let’s notice that under the risk neutral probability the actualised future price must be a martingale.
Applying Itô formula, ∀ t ∈ R \forall t \in \mathbb{R} ∀ t ∈ R
d ( e − r t V ( t , S t ) ) = − r e − r t V ( t , S t ) d t + e − r t ∂ V ( t , S t ) ∂ t d t + e − r t ∂ V ( t , S t ) ∂ S t d S t + e − r t ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 d t + e − r t Δ V ( t , S t ) − e − r t ∂ V ( t , S t ) ∂ S t Δ S t
\begin{align*}
d( e^{-rt} V(t,S_t)) = & -r e^{-rt}V(t,S_t) dt + e^{-rt} \frac{\partial V(t,S_t)}{\partial t}dt + e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} dS_t \\
& + e^{-rt}\frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} dt + e^{-rt} \Delta V(t,S_t) - e^{-rt} \frac{\partial V(t,S_t)}{\partial S_t}\Delta S_t
\end{align*}
d ( e − r t V ( t , S t )) = − r e − r t V ( t , S t ) d t + e − r t ∂ t ∂ V ( t , S t ) d t + e − r t ∂ S t ∂ V ( t , S t ) d S t + e − r t ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 d t + e − r t Δ V ( t , S t ) − e − r t ∂ S t ∂ V ( t , S t ) Δ S t With:
d S t = S t − [ r d t + σ d W t + ∫ R ( e x − 1 ) J ~ X ( d t × d x ) ] Δ S t = S t − e Δ X t − S t − = ∫ R S t − ( e x − 1 ) J X ( d t × d x ) Δ V ( t , S t ) = V ( t , S t − e Δ X t ) − V ( t , S t − ) = ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] J X ( d t × d x )
\begin{align*}
dS_t & = S_t^- \left[ r dt + \sigma dW_t + \int\limits_{\mathbb{R}} (e^x - 1) \tilde{J}_X (dt \times dx) \right] \\
\Delta S_t & = S_{t^-}e^{\Delta X_t} - S_{t^-} = \int\limits_{\mathbb{R}} S_{t^-} (e^x - 1) J_X (dt \times dx) \\
\Delta V(t,S_t) & = V(t,S_{t^-}e^{\Delta X_t} ) - V(t,S_{t^-}) = \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] J_X (dt \times dx)
\end{align*}
d S t Δ S t Δ V ( t , S t ) = S t − r d t + σ d W t + R ∫ ( e x − 1 ) J ~ X ( d t × d x ) = S t − e Δ X t − S t − = R ∫ S t − ( e x − 1 ) J X ( d t × d x ) = V ( t , S t − e Δ X t ) − V ( t , S t − ) = R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] J X ( d t × d x ) By replacing:
d ( e − r t V ( t , S t ) ) = − r e − r t V ( t , S t ) d t + e − r t ∂ V ( t , S t ) ∂ t d t + e − r t ∂ V ( t , S t ) ∂ S t S t − [ r d t + σ d W t + ∫ R ( e x − 1 ) J ~ X ( d t × d x ) ] + e − r t ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 d t + e − r t ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] J X ( d x × d t ) − e − r t ∂ V ( t , S t ) ∂ S t ∫ R S t − ( e x − 1 ) J X ( d t × d x ) d ( e − r t V ( t , S t ) ) = − r e − r t V ( t , S t ) d t + e − r t ∂ V ( t , S t ) ∂ t d t + e − r t ∂ V ( t , S t ) ∂ S t S t − r d t + e − r t ∂ V ( t , S t ) ∂ S t S t − σ d W t + e − r t ∂ V ( t , S t ) ∂ S t S t − ∫ R ( e x − 1 ) J X ( d t × d x ) − e − r t ∂ V ( t , S t ) ∂ S t S t − ∫ R ( e x − 1 ) ν ( d t ) d x + e − r t ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 d t + e − r t ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] J X ( d t × d x ) − e − r t ∂ V ( t , S t ) ∂ S t ∫ R S t − ( e x − 1 ) J X ( d t × d x ) d ( e − r t V ( t , S t ) ) = − r e − r t V ( t , S t ) d t + e − r t ∂ V ( t , S t ) ∂ t d t + e − r t ∂ V ( t , S t ) ∂ S t S t − r d t + e − r t ∂ V ( t , S t ) ∂ S t S t − σ d W t − e − r t ∂ V ( t , S t ) ∂ S t S t − ∫ R ( e x − 1 ) ν ( d t ) d x + e − r t ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 d t + e − r t ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] J ~ X ( d t × d x ) + e − r t ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] ν ( d x ) d t
\begin{align*}
d( e^{-rt} V(t,S_t)) = & -r e^{-rt}V(t,S_t) dt + e^{-rt} \frac{\partial V(t,S_t)}{\partial t}dt + e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-[r dt + \sigma dW_t \\
& + \int\limits_{\mathbb{R}} (e^x - 1) \tilde{J}_X (dt \times dx)] + e^{-rt}\frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} dt \\
& + e^{-rt} \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] J_X (dx \times dt) \\
& - e^{-rt} \frac{\partial V(t,S_t)}{\partial S_t}\int\limits_{\mathbb{R}} S_{t^-} (e^x - 1) J_X (dt \times dx) \\
d( e^{-rt} V(t,S_t))= & -r e^{-rt}V(t,S_t) dt + e^{-rt} \frac{\partial V(t,S_t)}{\partial t}dt \\
& + e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-r dt + e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-\sigma dW_t \\
& + e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-\int\limits_{\mathbb{R}} (e^x - 1) J_X (dt \times dx) \\
& - e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-\int\limits_{\mathbb{R}} (e^x - 1) \nu (dt) dx \\
& + e^{-rt}\frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} dt + e^{-rt} \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] J_X (dt \times dx) \\
& - e^{-rt} \frac{\partial V(t,S_t)}{\partial S_t}\int\limits_{\mathbb{R}} S_{t^-} (e^x - 1) J_X (dt \times dx) \\
d( e^{-rt} V(t,S_t)) = & -r e^{-rt}V(t,S_t) dt + e^{-rt} \frac{\partial V(t,S_t)}{\partial t}dt \\
& + e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-r dt + e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-\sigma dW_t \\
& - e^{-rt}\frac{\partial V(t,S_t)}{\partial S_t} S_t^-\int\limits_{\mathbb{R}} (e^x - 1) \nu (dt) dx + e^{-rt}\frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} dt \\
& + e^{-rt} \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] \tilde{J}_X (dt \times dx) \\
& + e^{-rt} \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] \nu (dx) dt
\end{align*}
d ( e − r t V ( t , S t )) = d ( e − r t V ( t , S t )) = d ( e − r t V ( t , S t )) = − r e − r t V ( t , S t ) d t + e − r t ∂ t ∂ V ( t , S t ) d t + e − r t ∂ S t ∂ V ( t , S t ) S t − [ r d t + σ d W t + R ∫ ( e x − 1 ) J ~ X ( d t × d x )] + e − r t ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 d t + e − r t R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] J X ( d x × d t ) − e − r t ∂ S t ∂ V ( t , S t ) R ∫ S t − ( e x − 1 ) J X ( d t × d x ) − r e − r t V ( t , S t ) d t + e − r t ∂ t ∂ V ( t , S t ) d t + e − r t ∂ S t ∂ V ( t , S t ) S t − r d t + e − r t ∂ S t ∂ V ( t , S t ) S t − σ d W t + e − r t ∂ S t ∂ V ( t , S t ) S t − R ∫ ( e x − 1 ) J X ( d t × d x ) − e − r t ∂ S t ∂ V ( t , S t ) S t − R ∫ ( e x − 1 ) ν ( d t ) d x + e − r t ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 d t + e − r t R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] J X ( d t × d x ) − e − r t ∂ S t ∂ V ( t , S t ) R ∫ S t − ( e x − 1 ) J X ( d t × d x ) − r e − r t V ( t , S t ) d t + e − r t ∂ t ∂ V ( t , S t ) d t + e − r t ∂ S t ∂ V ( t , S t ) S t − r d t + e − r t ∂ S t ∂ V ( t , S t ) S t − σ d W t − e − r t ∂ S t ∂ V ( t , S t ) S t − R ∫ ( e x − 1 ) ν ( d t ) d x + e − r t ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 d t + e − r t R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] J ~ X ( d t × d x ) + e − r t R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] ν ( d x ) d t We can split the formula with a martingale part and a finite variation part. We have:
∀ t ∈ R , d A t = e − r t [ − r V ( t , S t ) d t + ∂ V ( t , S t ) ∂ t d t + ∂ V ( t , S t ) ∂ S t S t − r d t + ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 d t + ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] ν ( d x ) d t − ∂ V ( t , S t ) ∂ S t ∫ R S t − ( e x − 1 ) ν ( d x ) d t ] ∀ t ∈ R , d M t = e − r t [ ∂ V ( t , S t ) ∂ S t S t − σ d W t + ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] J ~ X ( d t × d x ) ]
\begin{align*}
\forall t \in \mathbb{R}, d A_t = & e^{-rt} \, [ \, -r V(t,S_t) dt + \frac{\partial V(t,S_t)}{\partial t}dt + \frac{\partial V(t,S_t)}{\partial S_t} S_{t^-} r dt + \frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} dt \\
& + \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] \nu (dx) dt - \frac{\partial V(t,S_t)}{\partial S_t}\int\limits_{\mathbb{R}} S_{t^-} (e^x - 1) \nu (dx) dt \, ] \\
\forall t \in \mathbb{R}, d M_t = & e^{-rt} \, [ \, \frac{\partial V(t,S_t)}{\partial S_t} S_{t^-} \sigma dW_t + \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] \tilde{J}_X (dt \times dx) \, ]
\end{align*}
∀ t ∈ R , d A t = ∀ t ∈ R , d M t = e − r t [ − r V ( t , S t ) d t + ∂ t ∂ V ( t , S t ) d t + ∂ S t ∂ V ( t , S t ) S t − r d t + ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 d t + R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] ν ( d x ) d t − ∂ S t ∂ V ( t , S t ) R ∫ S t − ( e x − 1 ) ν ( d x ) d t ] e − r t [ ∂ S t ∂ V ( t , S t ) S t − σ d W t + R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] J ~ X ( d t × d x ) ] with ∀ t ∈ R \forall t \in \mathbb{R} ∀ t ∈ R A t A_t A t ∀ t ∈ R \forall t \in \mathbb{R} ∀ t ∈ R M t M_t M t
We have to cancel the finite variation part. The partial integro-differential equation is therefore, ∀ t ∈ R \forall t \in \mathbb{R} ∀ t ∈ R
0 = e − r t [ − r V ( t , S t ) d t + ∂ V ( t , S t ) ∂ t d t + ∂ V ( t , S t ) ∂ S t S t − r d t + ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 d t + ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) ] ν ( d x ) d t − ∂ V ( t , S t ) ∂ S t ∫ R S t − ( e x − 1 ) ν ( d x ) d t ] r V ( t , S t ) = ∂ V ( t , S t ) ∂ t + ∂ V ( t , S t ) ∂ S t S t − r + ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 + ∫ R [ V ( t , S t − e x ) − V ( t , S t − ) − ∂ V ( t , S t ) ∂ S t S t − ( e x − 1 ) ] ν ( d x ) r V ( t , S t ) = ∂ V ( t , S t ) ∂ t + ∂ V ( t , S t ) ∂ S t S t − [ r + ∫ R S t − ( e x − 1 ) ν ( d x ) ] + ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2 + ∫ R V ( t , S t − e x ) − V ( t , S t − ) ν ( d x )
\begin{align*}
0 = & e^{-rt} \, [ \, -r V(t,S_t) dt + \frac{\partial V(t,S_t)}{\partial t}dt + \frac{\partial V(t,S_t)}{\partial S_t} S_{t^-} r dt + \frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} dt \\
& + \int\limits_{\mathbb{R}} [ V(t,S_{t^-}e^x ) - V(t,S_{t^-}) ] \nu (dx) dt - \frac{\partial V(t,S_t)}{\partial S_t}\int\limits_{\mathbb{R}} S_{t^-} (e^x - 1) \nu (dx) dt \, ] \\
r V(t,S_t) = & \frac{\partial V(t,S_t)}{\partial t} + \frac{\partial V(t,S_t)}{\partial S_t} S_{t^-} r + \frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} \\
& + \int\limits_{\mathbb{R}} \, [ \, V(t,S_{t^-}e^x ) - V(t,S_{t^-}) - \frac{\partial V(t,S_t)}{\partial S_t} S_{t^-} (e^x - 1) \, ] \, \nu (dx) \\
r V(t,S_t) = & \frac{\partial V(t,S_t)}{\partial t} + \frac{\partial V(t,S_t)}{\partial S_t} S_{t^-} \, [ \, r + \int\limits_{\mathbb{R}} \, S_{t^-} (e^x - 1) \, \nu (dx) \, ] \, \\
& + \frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2} + \int\limits_{\mathbb{R}} V(t,S_{t^-}e^x ) - V(t,S_{t^-}) \, \nu (dx)
\end{align*}
0 = r V ( t , S t ) = r V ( t , S t ) = e − r t [ − r V ( t , S t ) d t + ∂ t ∂ V ( t , S t ) d t + ∂ S t ∂ V ( t , S t ) S t − r d t + ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 d t + R ∫ [ V ( t , S t − e x ) − V ( t , S t − )] ν ( d x ) d t − ∂ S t ∂ V ( t , S t ) R ∫ S t − ( e x − 1 ) ν ( d x ) d t ] ∂ t ∂ V ( t , S t ) + ∂ S t ∂ V ( t , S t ) S t − r + ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 + R ∫ [ V ( t , S t − e x ) − V ( t , S t − ) − ∂ S t ∂ V ( t , S t ) S t − ( e x − 1 ) ] ν ( d x ) ∂ t ∂ V ( t , S t ) + ∂ S t ∂ V ( t , S t ) S t − [ r + R ∫ S t − ( e x − 1 ) ν ( d x ) ] + ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 + R ∫ V ( t , S t − e x ) − V ( t , S t − ) ν ( d x ) Remark:
If the Lévy measure is always equals to 0 then the PIDE is in fact the well known PDE applying to continuous Lévy processes.
For d S t S t = r d t + σ d W t \frac{d S_t}{S_t} = r dt + \sigma d W_t S t d S t = r d t + σ d W t
∀ t ∈ R , r V ( t , S t ) = ∂ V ( t , S t ) ∂ t + ∂ V ( t , S t ) ∂ S t S t r + ∂ 2 V ( t , S t ) ∂ S t 2 σ 2 2
\forall t \in \mathbb{R},
r V(t,S_t) = \displaystyle \frac{\partial V(t,S_t)}{\partial t} + \frac{\partial V(t,S_t)}{\partial S_t} S_t r + \frac{\partial^2 V(t,S_t)}{\partial S_t^{\,\,2}} \frac{\sigma^2}{2}
∀ t ∈ R , r V ( t , S t ) = ∂ t ∂ V ( t , S t ) + ∂ S t ∂ V ( t , S t ) S t r + ∂ S t 2 ∂ 2 V ( t , S t ) 2 σ 2 Jump diffusion models
We decide to focus ourselves on a subset of jump diffusion models.
We expose the advantage of introducing jumps in the underlyings dynamic.
We find the dynamic and the risk neutral probability.
The reader can expand/collapse for more information
Why Jump diffusion models?
Empirically we observe the following characteristic for the underlying returns:
They don’t follow a log normal law. We observe heavy-tailed distribution and the kurtosis is not null
They are not continuous
We observe the volatility clustering phenomenon
Underlyings dynamic (for finite activity)
Let W W W J J J ( F t ) = ( σ ( W s ) s ≤ t ) ∨ ( σ ( J s ) s ≤ t ) (\mathcal{F}_t) = ( \sigma(W_s)_{s \le t} ) \lor ( \sigma(J_s)_{s \le t} ) ( F t ) = ( σ ( W s ) s ≤ t ) ∨ ( σ ( J s ) s ≤ t ) ∨ \lor ∨ F 1 ∨ F 2 \mathcal{F}_1 \lor \mathcal{F}_2 F 1 ∨ F 2 F 1 ⋃ F 2 \mathcal{F}_1 \bigcup \mathcal{F}_2 F 1 ⋃ F 2
The dynamic in the jump model framework is split in two parts: a continuous diffusion part and a jump part.
the dynamic under the risk neutral probability is:
d S t S t − = μ ( t − , S t − ) d t + σ ( t − , S t − ) d W t ⏟ c o n t i n u o u s p a r t + d J t ⏟ j u m p p a r t with J t = ∑ i = 1 N t ( A i − 1 )
\displaystyle \frac{d S_t}{S_{t^{-}}} =\underbrace{\mu (t^{-},S_{t^{-}}) dt + \sigma ({t^{-}},S_{t^{-}}) d W_t}_{continuous \; part} + \underbrace{d J_t}_{jump \; part}
\text{with } J_t = \displaystyle \sum_{ i = 1}^{N_t} ( A_i - 1 )
S t − d S t = co n t in u o u s p a r t μ ( t − , S t − ) d t + σ ( t − , S t − ) d W t + j u m p p a r t d J t with J t = i = 1 ∑ N t ( A i − 1 ) let’s note d S t S t − = d X t \displaystyle \frac{d S_t}{S_{t^{-}}} = d X_t S t − d S t = d X t
d X t c = μ ( t − , S t − ) d t + σ ( t − , S t − ) d W t d X_t^c = \mu ({t^{-}},S_{t^{-}}) dt + \sigma ({t^-},S_{t^-}) d W_t d X t c = μ ( t − , S t − ) d t + σ ( t − , S t − ) d W t X t c − X 0 c = ∫ 0 t μ ( s − , S s − ) d s + ∫ 0 t σ ( s − , S s − ) d W s X_t^c - X_0^c = \displaystyle \int\limits_0^t \mu ({s^{-}},S_{s^{-}}) ds + \displaystyle \int\limits_0^t \sigma ({s^{-}},S_{s^{-}}) d W_s X t c − X 0 c = 0 ∫ t μ ( s − , S s − ) d s + 0 ∫ t σ ( s − , S s − ) d W s d [ X ] t c = σ ( t − , S t − ) 2 d t d [X]_t^c = \sigma({t^{-}},S_{t^{-}})^2 d t d [ X ] t c = σ ( t − , S t − ) 2 d t [ X ] t c = ∫ 0 t σ ( s − , S s − ) 2 d s [X]_t^c = \displaystyle \int\limits_0^t \sigma ({s^{-}},S_{s^{-}})^2 ds [ X ] t c = 0 ∫ t σ ( s − , S s − ) 2 d s ∏ s ≤ t ( 1 + △ X s ) = ∏ i = 1 N t A i \displaystyle \prod_{ s \le t } ( 1 + \triangle X_s ) = \displaystyle \prod_{ i = 1 }^{N_t} A_i s ≤ t ∏ ( 1 + △ X s ) = i = 1 ∏ N t A i
The underlying price is:
S t = S 0 exp [ ∫ 0 t ( μ ( s − , S s − ) − σ ( s − , S s − ) 2 2 ) d s + ∫ 0 t σ ( s − , S s − ) d W s ] ∏ i = 1 N t A i
S_t = \displaystyle S_0 \exp \left[ \int\limits_{0}^t ( \mu ({s^-},S_{s^-}) - \frac{\sigma ({s^-},S_{s^-})^2}{2} ) \, \mathrm ds + \int\limits_{0}^t \sigma ({s^-},S_{s^-}) \, \mathrm d W_s \right] \displaystyle \prod_{i=1}^{N_t} A_i
S t = S 0 exp 0 ∫ t ( μ ( s − , S s − ) − 2 σ ( s − , S s − ) 2 ) d s + 0 ∫ t σ ( s − , S s − ) d W s i = 1 ∏ N t A i Risk neutral probabilities
Let’s note μ a = E [ A 1 ] = E [ A N t ] \mu_a = \mathbb{E} [ A_1] = \mathbb{E} [ A_{N_t}] μ a = E [ A 1 ] = E [ A N t ] ( J t − μ a ∫ 0 t λ ( s ) d s ) t ( J_t - \mu_a \displaystyle \int\limits_0^t \lambda (s) ds )_{t} ( J t − μ a 0 ∫ t λ ( s ) d s ) t F t \mathcal{F}_t F t
Let’s note M ( t ) = J t − μ a ∫ 0 t λ ( s ) d s M(t) = J_t - \mu_a \displaystyle \int\limits_0^t \lambda (s) ds M ( t ) = J t − μ a 0 ∫ t λ ( s ) d s
We have E [ J t ] = μ a ∫ 0 t λ ( s ) d s \mathbb{E} [ J_t ] = \mu_a \displaystyle \int\limits_0^t \lambda (s) ds E [ J t ] = μ a 0 ∫ t λ ( s ) d s
E [ M ( t ) ∣ F s ] = E [ J t − μ a ∫ 0 t λ ( s ) d s ∣ F s ] = E [ J t − J s − μ a ∫ s t λ ( u ) d u ∣ F s ] + J s − μ a ∫ 0 s λ ( u ) d u = E [ ∑ k = 1 + N s N t A i ∣ F s ] − μ a ∫ s t λ ( u ) d u ⏟ = 0 + J s − μ a ∫ 0 s λ ( u ) d u = J s − μ a ∫ 0 s λ ( u ) d u = M ( s )
\begin{align*}
\mathbb{E} [ M(t) \, | \, \mathcal{F}_s ] & = \mathbb{E} [ J_t - \mu_a \displaystyle \int\limits_0^t \lambda (s) ds \, | \, \mathcal{F}_s ] = \mathbb{E} [ J_t - J_s - \mu_a \displaystyle \int\limits_s^t \lambda (u) du \, | \, \mathcal{F}_s ] + J_s - \mu_a \displaystyle \int\limits_0^s \lambda (u) du \\
& = \underbrace{\mathbb{E} [ \displaystyle \sum_{k= 1+N_s}^{N_t} A_i \, | \, \mathcal{F}_s ] - \mu_a \displaystyle \int\limits_s^t \lambda (u) du }_{=0} + J_s - \mu_a \displaystyle \int\limits_0^s \lambda (u) du = J_s - \mu_a \displaystyle \int\limits_0^s \lambda (u) du = M(s)
\end{align*}
E [ M ( t ) ∣ F s ] = E [ J t − μ a 0 ∫ t λ ( s ) d s ∣ F s ] = E [ J t − J s − μ a s ∫ t λ ( u ) d u ∣ F s ] + J s − μ a 0 ∫ s λ ( u ) d u = = 0 E [ k = 1 + N s ∑ N t A i ∣ F s ] − μ a s ∫ t λ ( u ) d u + J s − μ a 0 ∫ s λ ( u ) d u = J s − μ a 0 ∫ s λ ( u ) d u = M ( s ) Because E [ M ( t ) ∣ F s ] = J s − μ a ∫ 0 s λ ( u ) d u = M ( s ) \mathbb{E} [ M(t) \, | \, \mathcal{F}_s ] = J_s - \mu_a \displaystyle \int\limits_0^s \lambda (u) du = M(s) E [ M ( t ) ∣ F s ] = J s − μ a 0 ∫ s λ ( u ) d u = M ( s ) d S t S t − = μ ( t − , S t − ) d t + σ ( t − , S t − ) d W t + d J t \frac{d S_t}{S_{t^{-}}} = \mu (t^{-},S_{t^{-}}) dt + \sigma ({t^{-}},S_{t^{-}}) d W_t + d J_t S t − d S t = μ ( t − , S t − ) d t + σ ( t − , S t − ) d W t + d J t
The discount factor is noted D t D_t D t D t = e − ∫ 0 t r ( s ) d s D_t = e^{ - \int\limits_{0}^t r(s) \, \mathrm ds} D t = e − 0 ∫ t r ( s ) d s
d ( D t S t ) = − r ( t ) D t S t d t + D t d S t D t S t = ∫ 0 t D s − S s − [ ( μ ( s − , S s − ) − r ( s ) ) d s + σ ( s − , S S − ) d W s + d J s ] + D 0 S 0 D t S t = ∫ 0 t D s − S s − [ μ ( s − , S s − ) + λ ( s − ) ( μ a − 1 ) − r ( s − ) ] d s + ∫ 0 t D s − S s − σ ( s − , S s − ) d W s + ∫ 0 t D s − S s − d M s + D 0 S 0
\begin{align*}
d ( D_t S_t ) & = - r(t) D_t S_t dt + D_t d S_t \\
D_t S_t & = \displaystyle \int\limits_0^t D_{s^-} S_{{s^-}} [ ( \mu (s^{-},S_{s^{-}})- r(s) ) ds + \sigma ({s^{-}},S_{S^{-}}) d W_s + d J_s ] + D_0 S_0 \\
D_t S_t & = \displaystyle \int\limits_0^t D_{s^-} S_{{s^-}} [ \mu (s^{-},S_{s^{-}}) + \lambda(s^-) (\mu_a - 1 ) - r(s^-) ] ds \\
& + \displaystyle \int\limits_0^t D_{s^-} S_{{s^-}} \sigma ({s^{-}},S_{s^{-}}) d W_s \displaystyle + \int\limits_0^t D_{s^-} S_{{s^-}} d M_s + D_0 S_0 \\
\end{align*}
d ( D t S t ) D t S t D t S t = − r ( t ) D t S t d t + D t d S t = 0 ∫ t D s − S s − [( μ ( s − , S s − ) − r ( s )) d s + σ ( s − , S S − ) d W s + d J s ] + D 0 S 0 = 0 ∫ t D s − S s − [ μ ( s − , S s − ) + λ ( s − ) ( μ a − 1 ) − r ( s − )] d s + 0 ∫ t D s − S s − σ ( s − , S s − ) d W s + 0 ∫ t D s − S s − d M s + D 0 S 0 Therefore
D t S t − ∫ 0 t D s − S s − σ ( s − , S s − ) d W s − ∫ 0 t D s − S s − d M s = ∫ 0 t D s − S s − [ μ ( s − , S s − ) + λ ( s − ) ( μ a − 1 ) − r ( s − ) ] d s + D 0 S 0
\begin{align*}
& D_t S_t - \displaystyle \int\limits_0^t D_{s^-} S_{{s^-}} \sigma ({s^{-}},S_{s^{-}}) d W_s - \displaystyle \int\limits_0^t D_{s^-} S_{{s^-}} d M_s \\
& = \displaystyle \int\limits_0^t D_{s^-} S_{{s^-}} [ \mu (s^{-},S_{s^{-}}) + \lambda(s^-) (\mu_a - 1 ) - r(s^-) ] ds + D_0 S_0
\end{align*}
D t S t − 0 ∫ t D s − S s − σ ( s − , S s − ) d W s − 0 ∫ t D s − S s − d M s = 0 ∫ t D s − S s − [ μ ( s − , S s − ) + λ ( s − ) ( μ a − 1 ) − r ( s − )] d s + D 0 S 0 On the left side is a linear combination of martingale (an integral again a martingale is still a martingale).
Therefore, the right side is also a martingale. We have:
∫ 0 ⋅ ( μ ( u − , S u − ) − r u − + λ u − [ μ a − 1 ] ) d u \int\limits_{0}^{\cdot} ( \mu ({u^-},S_{u^-}) - r_{u^-} + \lambda_{u^-} [ \mu_a - 1] \; )\, \mathrm du 0 ∫ ⋅ ( μ ( u − , S u − ) − r u − + λ u − [ μ a − 1 ] ) d u which is a martingale so:
∀ t ∈ R + , μ ( t , S t ) − r t + λ t [ μ a − 1 ] = 0 ⇔ ∀ t μ ( t , S t ) = r t − λ t [ μ a − 1 ] \forall t \in \mathbb{R}^+ ,\; \mu (t,S_t) - r_t + \lambda_{t} [ \mu_a - 1] = 0
\Leftrightarrow \; \forall t \; \mu (t,S_t) = r_t - \lambda_{t} [ \mu_a - 1] ∀ t ∈ R + , μ ( t , S t ) − r t + λ t [ μ a − 1 ] = 0 ⇔ ∀ t μ ( t , S t ) = r t − λ t [ μ a − 1 ] Under the risk neutral probability, the underlying price is:
S t = S 0 exp [ ∫ 0 t ( r u − − λ u − [ μ a − 1 ] − σ ( u − , S u − ) 2 2 ) d u + ∫ 0 t σ ( u − , S u − ) d W u ] ∏ i = 1 N t A i
S_t = S_0 \displaystyle \exp \left[ \int\limits_{0}^t \left( r_{u^-} - \lambda_{u^-} [ \mu_a - 1] - \frac{\sigma ({u^-},S_{u^-})^2}{2} \right) \, \mathrm du + \int\limits_{0}^t \sigma ({u^-},S_{u^-}) \, \mathrm d W_u \right] \displaystyle \prod_{i=1}^{N_t} A_i
S t = S 0 exp 0 ∫ t ( r u − − λ u − [ μ a − 1 ] − 2 σ ( u − , S u − ) 2 ) d u + 0 ∫ t σ ( u − , S u − ) d W u i = 1 ∏ N t A i Merton jump diffusion model
A model having this features is the Merton model.
We expose the dynamic of the underlyings and the european call price formula.
We also investigate the calibration procedure in this model.
The dynamic in this model is the following one:
d S t S t − = ( r t − − λ t − [ μ a − 1 ] ) d t + σ t − d W t + d J t \frac{d S_t}{S_{t^{-}}} = ( r_{t^-} - \lambda_{t^-} [ \mu_a - 1] ) dt + \sigma_{t^-} d W_t + d J_t S t − d S t = ( r t − − λ t − [ μ a − 1 ]) d t + σ t − d W t + d J t with
the interest rate r r r σ \sigma σ
∀ μ z , σ z ∈ R 2 A i = e μ z + σ z Z i \forall \mu_z, \sigma_z \in \mathbb{R}^2 A_i = e^{\mu_z + \sigma_z Zi} ∀ μ z , σ z ∈ R 2 A i = e μ z + σ z Z i ∀ n , ( Z 1 , … , Z n ) ∼ N ( 0 , I n ) \forall n, (Z_1, \ldots ,Z_n ) \sim \mathcal{N}(0, I_n) ∀ n , ( Z 1 , … , Z n ) ∼ N ( 0 , I n ) ∀ i ∈ N ∗ , ∀ t ∈ R + , A i ⊥ ⊥ N t \forall i \in \mathbb{N}^*, \forall t \in \mathbb{R}^+, A_i \perp\!\!\!\perp N_t ∀ i ∈ N ∗ , ∀ t ∈ R + , A i ⊥ ⊥ N t μ a = e x p ( μ z + σ z 2 2 ) \mu_a = exp( \mu_z + \frac{\sigma_z^2}{2} ) μ a = e x p ( μ z + 2 σ z 2 )
The underlying price is
S t = S 0 exp ( ∫ 0 t ( r s − − λ s − [ μ a − 1 ] − σ s − 2 2 ) d s + ∫ 0 t σ s − d W s ) ∏ i = 1 N t A i = S 0 exp ( ∫ 0 t ( r s − − λ s − [ μ a − 1 ] − σ s − 2 2 ) d s + ∫ 0 t σ s − d W s + ∑ i = 1 N t [ μ z + σ z Z i ] )
\begin{align*}
S_t & = \displaystyle S_0 \exp \left( \int\limits_{0}^t ( r_{s^-} - \lambda_{s^-} [ \mu_a - 1] - \frac{\sigma_{s^-}^2}{2} ) \, \mathrm ds + \int\limits_{0}^t \sigma_{s^-} \, \mathrm d W_s \right) \displaystyle \prod_{i=1}^{N_t} A_i \\
& = S_0 \exp \left( \, \int\limits_{0}^t ( r_{s^-} - \lambda_{s^-} [ \mu_a - 1] - \frac{\sigma_{s^-}^2}{2} ) \, \mathrm ds + \int\limits_{0}^t \sigma_{s^-} \, \mathrm d W_s + \displaystyle \sum_{i=1}^{N_t} [ \mu_z + \sigma_z \; Z_i ] \, \right)
\end{align*}
S t = S 0 exp 0 ∫ t ( r s − − λ s − [ μ a − 1 ] − 2 σ s − 2 ) d s + 0 ∫ t σ s − d W s i = 1 ∏ N t A i = S 0 exp 0 ∫ t ( r s − − λ s − [ μ a − 1 ] − 2 σ s − 2 ) d s + 0 ∫ t σ s − d W s + i = 1 ∑ N t [ μ z + σ z Z i ] European call price
We expose in this section three different methods to compute a call price in the Merton model:
Monte-Carlo
PIDE
Series expansion
For Monte-Carlo and PIDE methods, we refer the reader to the book of R. Cont and P. Tankov:
“Financial Modelling with Jump Processes”.
The reader can expand/collapse for more information on the series expansion method
Let’s compute the call price under the risk neutral probability previously exposed.
A same computation can be apply for Put price.
The steps are the followings:
Apply the law of iterated expectations using the Poisson process conditioning
Compute the new log normal parameters
Compute the expected value of a Black-Scholes call as a function of the Poisson law
Let’s compute the call price:
E [ e − ∫ s t r u d u ( S t − K ) + ∣ F s ] = E [ E [ e − ∫ s t r u d u ( S t − K ) + ∣ N t = n ] ∣ F s ]
\mathbb{E} \left[ e^{ - \int\limits_{s}^t r_u \mathrm du } \; ( S_t - K )_{+} \, | \, \mathcal{F}_s \right] = \mathbb{E} \left[ \; \mathbb{E} [ \; e^{ - \int\limits_{s}^t r_u \mathrm du } \; ( S_t - K )_{+} | N_t =n \; ] \; \, | \, \mathcal{F}_s \right]
E e − s ∫ t r u d u ( S t − K ) + ∣ F s = E E [ e − s ∫ t r u d u ( S t − K ) + ∣ N t = n ] ∣ F s Let’s identify the law of S t S_t S t N t = n N_t = n N t = n
S t ∣ N t , F s = L S s exp ( ∫ s t ( r u − − λ u − [ μ a − 1 ] − σ u − 2 2 ) d u + ∫ s t σ u − d W u + n μ z + n σ z Z 1 )
S_t | N_t , \mathcal{F}_s \overset{\mathcal{L}}{=} S_s \exp \left( \; \int\limits_{s}^t ( r_{u^-} - \lambda_{u^-} [ \mu_a - 1] - \frac{\sigma_{u^-}^2}{2} ) \, \mathrm du + \int\limits_{s}^t \sigma_{u^-} \, \mathrm d W_u + n \mu_z + \sqrt{n} \sigma_z \; Z_1 \; \right)
S t ∣ N t , F s = L S s exp s ∫ t ( r u − − λ u − [ μ a − 1 ] − 2 σ u − 2 ) d u + s ∫ t σ u − d W u + n μ z + n σ z Z 1 Moreover, we know that ∫ s t σ u d W u ∼ N ( 0 , ∫ s t σ u 2 d u ) \int\limits_{s}^t \sigma_u \, \mathrm d W_u \sim N ( 0 , \int\limits_{s}^t \sigma_u^2 \, \mathrm du ) s ∫ t σ u d W u ∼ N ( 0 , s ∫ t σ u 2 d u )
Let’s write the integral against the brownian motion using law equalities:
∫ s t σ u − d W u + n σ z L = L ( ∫ s t σ u − 2 d u + n σ z 2 ) L = L ( ∫ s t σ u − 2 d u + n σ z 2 ) ( W t − W s ) t − s = L 1 t − s ( ∫ s t σ u − 2 d u + n σ z 2 ) ( W t − W s )
\begin{align*}
\int\limits_{s}^t \sigma_{u^-} \, \mathrm d W_u + \sqrt{n} \sigma_z L &\overset{\mathcal{L}}{=} \sqrt{ ( \int\limits_{s}^t \sigma_{u^-}^2 \, \mathrm du + n \sigma_z^2 } ) \; L \overset{\mathcal{L}}{=} \sqrt{( \int\limits_{s}^t \sigma_{u^-}^2 \, \mathrm du + n \sigma_z^2 )} \; \frac{( W_t - W_s )}{ \sqrt{t-s} }\\
&\overset{\mathcal{L}}{=} \sqrt{ \frac{1}{ t - s } \left( \int\limits_{s}^t \sigma_{u^-}^2 \, \mathrm du + n \sigma_z^2 \right) } ( W_t - W_s )
\end{align*}
s ∫ t σ u − d W u + n σ z L = L ( s ∫ t σ u − 2 d u + n σ z 2 ) L = L ( s ∫ t σ u − 2 d u + n σ z 2 ) t − s ( W t − W s ) = L t − s 1 s ∫ t σ u − 2 d u + n σ z 2 ( W t − W s ) with L L L
S t ∣ N t , F s = L S s exp ( ∫ s t ( r u − − λ u − [ μ a − 1 ] − σ u − 2 2 ) d u + n μ z + ∫ s t σ u − 2 d u t − s + n σ z 2 t − s ( W t − W s ) )
S_t | N_t , \mathcal{F}_s \overset{\mathcal{L}}{=} S_s \exp \left( \; \int\limits_{s}^t ( r_{u^-} - \lambda_{u^-} [ \mu_a - 1] - \frac{\sigma_{u^-}^2}{2} ) \, \mathrm du + n \mu_z + \sqrt{ \frac{\int\limits_{s}^t \sigma_{u^-}^2 \, \mathrm du }{ t - s } + \frac{n \sigma_z^2}{ t - s } } \; ( W_t - W_s ) \; \right)
S t ∣ N t , F s = L S s exp s ∫ t ( r u − − λ u − [ μ a − 1 ] − 2 σ u − 2 ) d u + n μ z + t − s s ∫ t σ u − 2 d u + t − s n σ z 2 ( W t − W s ) S t ∣ N t , F s = L S s exp ( n μ z − ∫ s t λ u − d u [ μ a − 1 ] + n σ z 2 2 ) exp ( ∫ s t r u − − σ u − 2 2 d u − n σ z 2 2 + ∫ s t σ u − 2 d u t − s + n σ z 2 t − s ( W t − W s ) )
\begin{align*}
S_t | N_t , \mathcal{F}_s \overset{\mathcal{L}}{=} S_s & \exp \left( n \mu_z - \int\limits_{s}^t \lambda_{u^-} du [ \mu_a - 1] + \frac{n \sigma_z^2}{ 2 } \right) \\
& \exp \left( \; \int\limits_{s}^t r_{u^-} - \frac{\sigma_{u^-}^2}{2} \, \mathrm du - \frac{n \sigma_z^2}{ 2 } + \sqrt{ \frac{\int\limits_{s}^t \sigma_{u^-}^2 \, \mathrm du }{ t - s } + \frac{n \sigma_z^2}{ t - s } } \; ( W_t - W_s ) \; \right)
\end{align*}
S t ∣ N t , F s = L S s exp n μ z − s ∫ t λ u − d u [ μ a − 1 ] + 2 n σ z 2 exp s ∫ t r u − − 2 σ u − 2 d u − 2 n σ z 2 + t − s s ∫ t σ u − 2 d u + t − s n σ z 2 ( W t − W s ) We can therefore note S ˉ s ( n ) \bar S_s (n) S ˉ s ( n ) S s S_s S s σ ˉ ( n ) \bar \sigma (n) σ ˉ ( n ) σ t \sigma_t σ t
S ˉ s ( n ) = S s exp ( ∫ s t λ u − d u [ 1 − μ a ] + n μ z + n σ z 2 2 ) σ ˉ ( n ) = n σ z 2 t − s + ∫ s t σ s − 2 d s t − s
\begin{align*}
\bar S_s (n) & = S_s \exp \left( \int\limits_{s}^t \lambda_{u^-} du [1 -\mu_a] + n \mu_z + \frac{n \sigma_z^2}{ 2 } \right) \\
\bar \sigma (n) & = \sqrt{ \frac{n \sigma_z^2 }{t-s} + \frac{ \int\limits_{s}^t \sigma_{s^-}^2 ds}{t-s} }
\end{align*}
S ˉ s ( n ) σ ˉ ( n ) = S s exp s ∫ t λ u − d u [ 1 − μ a ] + n μ z + 2 n σ z 2 = t − s n σ z 2 + t − s s ∫ t σ s − 2 d s We have:
S t ∣ N t , F s = L S ˉ s ( N t ) exp ( ∫ s t r u − d u − σ ˉ ( N t ) 2 2 ( t − s ) + σ ˉ ( N t ) ( W t − W s ) )
S_t | N_t , \mathcal{F}_s \overset{\mathcal{L}}{=} \bar S_s (N_t) \exp \left( \; \int\limits_{s}^t r_{u^-} \, \mathrm du - \frac{ \bar \sigma (N_t)^2}{2} (t-s) + \bar \sigma (N_t) \; (W_t - W_s) \; \right)
S t ∣ N t , F s = L S ˉ s ( N t ) exp s ∫ t r u − d u − 2 σ ˉ ( N t ) 2 ( t − s ) + σ ˉ ( N t ) ( W t − W s ) Let’s back to the initial conditional expectation:
E [ E [ e − ∫ s t r u d u ( S t − K ) + ∣ N t = n ] ∣ F s ] = E [ C B S ( S s ˉ ( k ) , K , r , t , σ ˉ ( k ) ) ∣ F s ]
\mathbb{E} \left[ \; \mathbb{E} \left[ e^{- \int\limits_{s}^t r_u \mathrm du } \; ( S_t - K )_{+} | N_t =n \; \right] \; | \mathcal{F}_s \right] = \mathbb{E} \left[ C_{BS}( \bar{S_s}(k),K,r,t,\bar{\sigma}(k)) | \mathcal{F}_s \right]
E E e − s ∫ t r u d u ( S t − K ) + ∣ N t = n ∣ F s = E [ C B S ( S s ˉ ( k ) , K , r , t , σ ˉ ( k )) ∣ F s ] Under the Black-Scholes model, we recall the european call closed form:
C B S ( S s , K , r , T , σ ) = S s N ( d 1 ) − K e x p ( − r T ) N ( d 2 ) d 1 = 1 σ T [ l n ( S s K ) + ( r + σ 2 2 ) T ] d 2 = d 1 − σ T
\begin{align*}
C_{BS} & ( S_s, K, r, T,\sigma ) = S_s N(d1) - K exp(-r T) N(d2) \\
d1 & = \frac{1}{\sigma \sqrt{T}} [ ln( \frac{S_s}{K} ) + ( r + \frac{\sigma^2}{2} ) T ] \\
d2 & = d1 - \sigma \sqrt{T}
\end{align*}
C B S d 1 d 2 ( S s , K , r , T , σ ) = S s N ( d 1 ) − K e x p ( − r T ) N ( d 2 ) = σ T 1 [ l n ( K S s ) + ( r + 2 σ 2 ) T ] = d 1 − σ T We therefore have to compute the C B S C_{BS} C B S
The Merton call price is given by:
C a l l ( s , T , S , K ) = ∑ k = 0 ∞ P ( N t = k ) × C B S ( S s ˉ ( N t ) , K , r , t , σ ˉ ( N t ) ) Call (s,T,S,K) = \displaystyle \sum_{k = 0}^{\infty} \mathbb{P} ( N_t = k ) \times C_{BS}( \bar{S_s}(N_t),K,r,t,\bar{\sigma}(N_t) ) C a l l ( s , T , S , K ) = k = 0 ∑ ∞ P ( N t = k ) × C B S ( S s ˉ ( N t ) , K , r , t , σ ˉ ( N t )) Error control in call pricing
We have to find a stopping criteria for the previous series expansion, we want to identify k o p t k_{opt} k o pt
E r r ( k o p t ) = ∣ 1 S 0 ( ∑ k = 0 ∞ f ( k ) − ∑ k = 0 k o p t f ( k ) ) ∣ < ϵ f ( k ) = P ( N t = k ) × T ( k ) T ( k ) = C B S ( S s ˉ ( k ) , K , r , t , σ ˉ ( k ) )
\begin{align*}
Err (k_{opt}) = & |\frac{1}{S_0} ( \displaystyle \sum_{k = 0}^{\infty} f(k) - \displaystyle \sum_{k = 0}^{k_{opt}} f(k) ) | < \epsilon \\
f(k) = & \mathbb{P} ( N_t = k ) \times T(k) \\
T(k) = & C_{BS}( \bar{S_s}(k),K,r,t,\bar{\sigma}(k))
\end{align*}
E r r ( k o pt ) = f ( k ) = T ( k ) = ∣ S 0 1 ( k = 0 ∑ ∞ f ( k ) − k = 0 ∑ k o pt f ( k )) ∣ < ϵ P ( N t = k ) × T ( k ) C B S ( S s ˉ ( k ) , K , r , t , σ ˉ ( k )) Let’s suppose λ \lambda λ
S 0 × E r r ( k ) = ∣ ∑ k = 0 ∞ e − λ t ( λ t ) k k ! T ( k ) − ∑ k = 0 k o p t e − λ t ( λ t ) k k ! T ( k ) ∣ = ∣ ∑ k = k o p t + 1 ∞ e − λ t ( λ t ) k k ! T ( k ) ∣ = ∣ ∑ k = k o p t + 1 ∞ P ( N t = k ) T ( k ) ∣
\begin{align*}
S_0 \times Err(k) & = | \displaystyle \sum_{k = 0}^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } T(k) - \displaystyle \sum_{k = 0}^{k_{opt}} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } T(k) | = | \displaystyle \sum_{k = k_{opt}+1 }^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } T(k)| \\
& = | \displaystyle \sum_{k = k_{opt}+1 }^{\infty} \mathbb{P} ( N_t = k ) T(k)|
\end{align*}
S 0 × E r r ( k ) = ∣ k = 0 ∑ ∞ e − λ t k ! ( λ t ) k T ( k ) − k = 0 ∑ k o pt e − λ t k ! ( λ t ) k T ( k ) ∣ = ∣ k = k o pt + 1 ∑ ∞ e − λ t k ! ( λ t ) k T ( k ) ∣ = ∣ k = k o pt + 1 ∑ ∞ P ( N t = k ) T ( k ) ∣ Using the non arbitrary conditions, we can write T ( k ) ≤ S 0 ˉ T(k) \le \bar{S_0} T ( k ) ≤ S 0 ˉ
Moreover, all the terms of the sum are positive, so:
S 0 × E r r ( k ) ≤ ∑ k = k o p t + 1 ∞ e − λ t ( λ t ) k k ! S ˉ 0 = e − λ t ∑ k = k o p t + 1 ∞ ( λ t ) k k ! S 0 exp ( λ t [ 1 − μ a ] + k μ z + k σ z 2 2 )
S_0 \times Err(k) \le \displaystyle \sum_{k = k_{opt}+1 }^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } \bar{S}_0
= {e^{-\lambda t}} \displaystyle \sum_{k = k_{opt}+1 }^{\infty} {\frac{(\lambda t)^k}{k!} } S_0 \exp ( \lambda t [1 -\mu_a] + k \mu_z + \frac{k \sigma_z^2}{ 2 } )
S 0 × E r r ( k ) ≤ k = k o pt + 1 ∑ ∞ e − λ t k ! ( λ t ) k S ˉ 0 = e − λ t k = k o pt + 1 ∑ ∞ k ! ( λ t ) k S 0 exp ( λ t [ 1 − μ a ] + k μ z + 2 k σ z 2 )
= e − λ t μ a ∑ k = k o p t + 1 ∞ ( λ t ) k k ! S 0 exp ( k μ z + k σ z 2 2 ) = S 0 e − λ t μ a ∑ k = k o p t + 1 ∞ ( λ t ) k k ! μ a k
= {e^{ - \lambda t \mu_a } } \displaystyle \sum_{k = k_{opt}+1 }^{\infty} {\frac{(\lambda t)^k}{k!} } S_0 \exp ( k \mu_z + \frac{k \sigma_z^2}{ 2 } )
= S_0 {e^{- \lambda t \mu_a } } \displaystyle \sum_{k = k_{opt}+1 }^{\infty} {\frac{(\lambda t)^k}{k!} } \mu_a^k
= e − λ t μ a k = k o pt + 1 ∑ ∞ k ! ( λ t ) k S 0 exp ( k μ z + 2 k σ z 2 ) = S 0 e − λ t μ a k = k o pt + 1 ∑ ∞ k ! ( λ t ) k μ a k Let’s note y = λ t μ a y = \lambda t \mu_a y = λ t μ a
S 0 × E r r ( k o p t ) ≤ S 0 e − y ∑ k = k o p t + 1 ∞ y k k ! = S 0 e − y [ e y − ∑ k = 0 k o p t y k k ! ]
S_0 \times Err ( k_{opt} ) \le S_0 {e^{-y} } \displaystyle \sum_{k = k_{opt}+1 }^{\infty} {\frac{y^k}{k!} }
= S_0 {e^{-y} } [ e^{y} - \displaystyle \sum_{k = 0 }^{k_{opt}} {\frac{y^k}{k!} } ]
S 0 × E r r ( k o pt ) ≤ S 0 e − y k = k o pt + 1 ∑ ∞ k ! y k = S 0 e − y [ e y − k = 0 ∑ k o pt k ! y k ]
E r r ( k o p t ) ≤ e − y [ e y − ∑ k = 0 k o p t y k k ! ] Err ( k_{opt} ) \le {e^{-y} } [ e^{y} - \displaystyle \sum_{k = 0 }^{k_{opt}} {\frac{y^k}{k!} } ] E r r ( k o pt ) ≤ e − y [ e y − k = 0 ∑ k o pt k ! y k ] We simply have to test if e y − ∑ k = 0 k o p t ( y ) k k ! e^{y} - \displaystyle \sum_{k = 0}^{k_{opt}}{\frac{(y)^k}{k!} } e y − k = 0 ∑ k o pt k ! ( y ) k
Numerically, this sum can be directly computed. We have to accumulate the term inside the price computation.
Greeks computation
Greeks can be computed using a closed form by applying the chain rule.
The reader can expand/collapse for more details on greeks.
δ = ∂ C a l l ∂ S = ∑ k = 0 ∞ e − λ t ( λ t ) k k ! × δ B S ( k ) × exp ( ∫ 0 t λ s d s [ 1 − μ a ] + k μ z + k σ z 2 2 ) γ = ∂ 2 C a l l ∂ S 2 = ∑ k = 0 ∞ e − λ t ( λ t ) k k ! × γ B S ( k ) × exp ( 2 [ ∫ 0 t λ s d s [ 1 − μ a ] + k μ z + k σ z 2 2 ] ) v e g a = ∂ C a l l ∂ σ = ∑ k = 0 ∞ e − λ t ( λ t ) k k ! × v e g a B S ( k ) × σ t t n σ z 2 + ∫ 0 t σ t 2 ∂ C a l l ∂ K = ∑ k = 0 ∞ e − λ t ( λ t ) k k ! × ∂ C B S ∂ K ( k ) ∂ 2 C a l l ∂ K 2 = ∑ k = 0 ∞ e − λ t ( λ t ) k k ! × ∂ 2 C B S ∂ K 2 ( k )
\begin{align*}
\delta = \frac{\partial Call }{\partial S } = &
\displaystyle \sum_{k = 0}^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } \times \delta^{BS}(k)
\times \exp \left( \int\limits_{0}^t \lambda_s ds [1 -\mu_a] + k \mu_z + \frac{k \sigma_z^2}{ 2 } \right) \\
\gamma = \frac{\partial^2 Call }{\partial S^2 } = &
\displaystyle \sum_{k = 0}^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } \times \gamma^{BS}(k)
\times \exp \left( 2 [ \int\limits_{0}^t \lambda_s ds [1 -\mu_a] + k \mu_z + \frac{k \sigma_z^2}{ 2 } ] \right) \\
vega = \frac{\partial Call }{\partial \sigma } = &
\displaystyle \sum_{k = 0}^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } \times vega^{BS}(k) \times \frac{\sigma_t \sqrt{t}} {n \sigma_z^2 + \int\limits_{0}^t \sigma_t^2 } \\
\frac{\partial Call }{\partial K } & = \displaystyle \sum_{k = 0}^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } \times \frac{\partial C_{BS}}{\partial K }(k) \\
\frac{\partial^2 Call }{\partial K^2 } & = \displaystyle \sum_{k = 0}^{\infty} {e^{-\lambda t}} {\frac{(\lambda t)^k}{k!} } \times \frac{\partial^2 C_{BS} }{\partial K^2 }(k)
\end{align*}
δ = ∂ S ∂ C a l l = γ = ∂ S 2 ∂ 2 C a l l = v e g a = ∂ σ ∂ C a l l = ∂ K ∂ C a l l ∂ K 2 ∂ 2 C a l l k = 0 ∑ ∞ e − λ t k ! ( λ t ) k × δ B S ( k ) × exp 0 ∫ t λ s d s [ 1 − μ a ] + k μ z + 2 k σ z 2 k = 0 ∑ ∞ e − λ t k ! ( λ t ) k × γ B S ( k ) × exp 2 [ 0 ∫ t λ s d s [ 1 − μ a ] + k μ z + 2 k σ z 2 ] k = 0 ∑ ∞ e − λ t k ! ( λ t ) k × v e g a B S ( k ) × n σ z 2 + 0 ∫ t σ t 2 σ t t = k = 0 ∑ ∞ e − λ t k ! ( λ t ) k × ∂ K ∂ C B S ( k ) = k = 0 ∑ ∞ e − λ t k ! ( λ t ) k × ∂ K 2 ∂ 2 C B S ( k ) Generic calibration procedure
Let introduce the classical calibration procedure.
arg p ∈ P min ∑ i ∈ I w i ( σ i m o d ( p ) − σ i m k t ) 2 \underset{p \in \mathcal{P}}{\arg} \min { \displaystyle \sum_{i \in I} w_i { ( \sigma_i^{mod}(p) - \sigma_i^{mkt} )^2 } } p ∈ P arg min i ∈ I ∑ w i ( σ i m o d ( p ) − σ i mk t ) 2
with
P \mathcal{P} P I I I ( w i ) i ∈ I {(w_i})_{i \in I} ( w i ) i ∈ I σ i m k t \sigma_i^{mkt} σ i mk t i t h i^{th} i t h σ i m o d ( p ) \sigma_i^{mod} (p) σ i m o d ( p ) p p p V i B S V_i^{BS} V i B S i t h i^{th} i t h V e g a B S i = ∂ V B S ∂ σ VegaBS_i = \displaystyle \frac{ \partial {V^{BS}} }{ \partial \sigma } V e g a B S i = ∂ σ ∂ V B S
By definition,
V i m o d = V i B S ( σ i m o d ( p ) ) V i m k t = V i B S ( σ i m k t )
\begin{align*}
& V_i^{mod} = V_i^{BS} (\sigma_i^{mod}(p)) \\
& V_i^{mkt} = V_i^{BS} (\sigma_i^{mkt})
\end{align*}
V i m o d = V i B S ( σ i m o d ( p )) V i mk t = V i B S ( σ i mk t ) Using Taylor series, we have:
V i B S ( σ i m o d ( p ) ) = V i B S ( σ i m k t ) + ( σ i m o d ( p ) − σ i m k t ) ∂ V i B S ∂ σ ( σ i m k t ) + O ( σ i m o d ( p ) − σ i m k t ) 2
V_i^{BS} (\sigma_i^{mod}(p)) = V_i^{BS} (\sigma_i^{mkt}) + ( \sigma_i^{mod}(p) - \sigma_i^{mkt} ) \displaystyle \frac{\partial V_i^{BS} }{\partial \sigma } (\sigma_i^{mkt}) + O ( \sigma_i^{mod}(p) - \sigma_i^{mkt} )^2
V i B S ( σ i m o d ( p )) = V i B S ( σ i mk t ) + ( σ i m o d ( p ) − σ i mk t ) ∂ σ ∂ V i B S ( σ i mk t ) + O ( σ i m o d ( p ) − σ i mk t ) 2 σ i m o d ( p ) − σ i m k t = V i B S ( σ i m o d ( p ) ) − V i B S ( σ i m k t ) ∂ V i B S ∂ σ ( σ i m k t ) + O ( σ i m o d ( p ) − σ i m k t ) 2 = V i B S ( σ i m o d ) ( p ) − V i B S ( σ i m k t ) V e g a B S i ( σ i m k t ) + O ( σ i m o d ( p ) − σ i m k t ) 2
\begin{align*}
\sigma_i^{mod}(p) - \sigma_i^{mkt} & = \displaystyle \frac{ V_i^{BS} (\sigma_i^{mod}(p)) - V_i^{BS} (\sigma_i^{mkt}) }{ \frac{\partial V_i^{BS} }{\partial \sigma } (\sigma_i^{mkt}) } + O ( \sigma_i^{mod}(p) - \sigma_i^{mkt} )^2 \\
& = \displaystyle \frac{ V_i^{BS} (\sigma_i^{mod})(p) - V_i^{BS} (\sigma_i^{mkt}) }{ VegaBS_i (\sigma_i^{mkt}) } + O ( \sigma_i^{mod}(p) - \sigma_i^{mkt} )^2
\end{align*}
σ i m o d ( p ) − σ i mk t = ∂ σ ∂ V i B S ( σ i mk t ) V i B S ( σ i m o d ( p )) − V i B S ( σ i mk t ) + O ( σ i m o d ( p ) − σ i mk t ) 2 = V e g a B S i ( σ i mk t ) V i B S ( σ i m o d ) ( p ) − V i B S ( σ i mk t ) + O ( σ i m o d ( p ) − σ i mk t ) 2 arg p ∈ P min ∑ i ∈ I w i [ V B S ( σ i m o d ( p ) ) − V B S ( σ i m k t ) V e g a B S i ( σ i m k t ) ] 2 \underset{p \in \mathcal{P}}{\arg} \min \displaystyle \sum_{i \in I} w_i \left[ { \frac{ V^{BS} (\sigma_i^{mod}(p)) - V^{BS} (\sigma_i^{mkt}) }{ VegaBS_i (\sigma_i^{mkt}) } } \right]^2 p ∈ P arg min i ∈ I ∑ w i [ V e g a B S i ( σ i mk t ) V B S ( σ i m o d ( p )) − V B S ( σ i mk t ) ] 2 Parameters impact
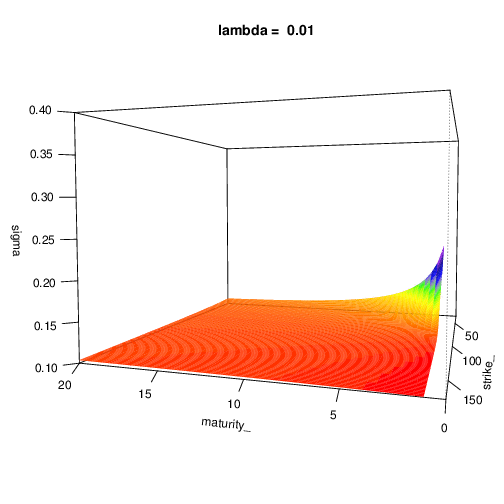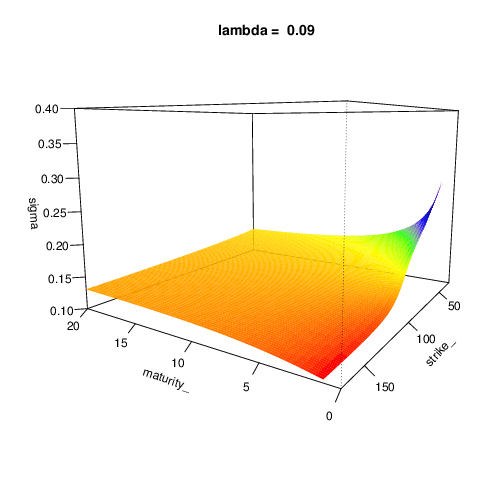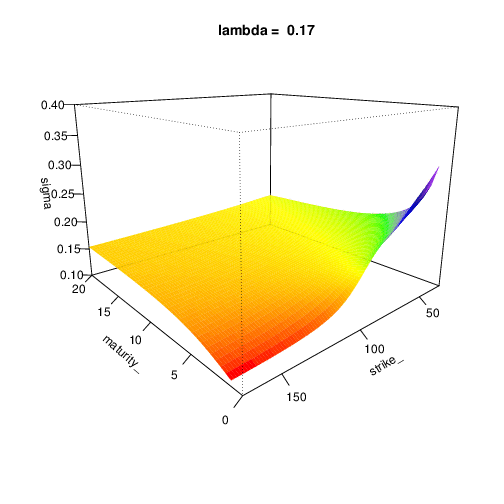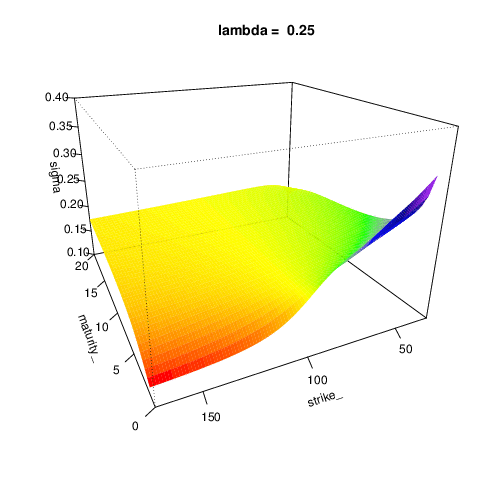
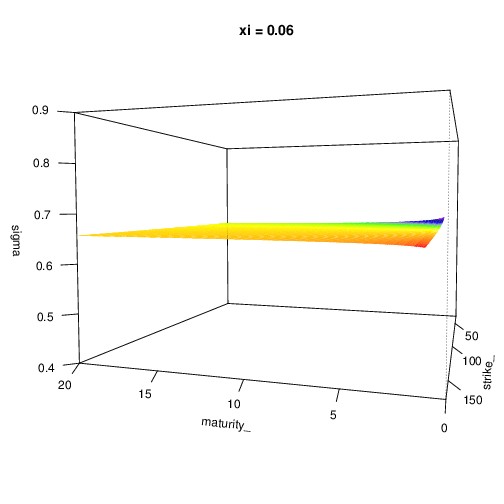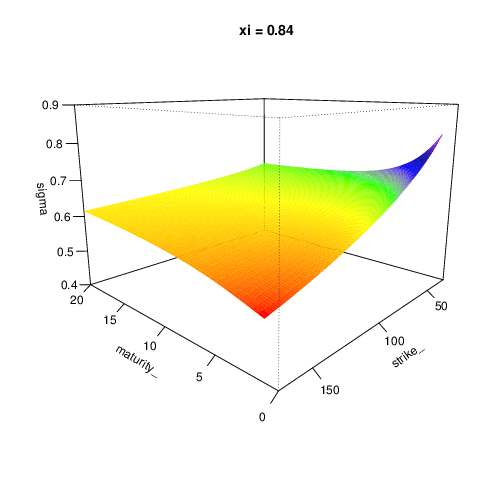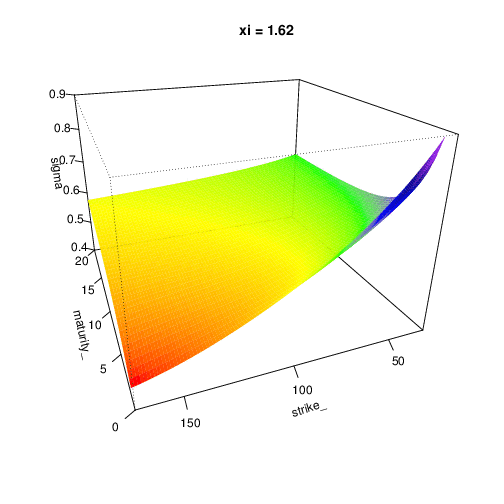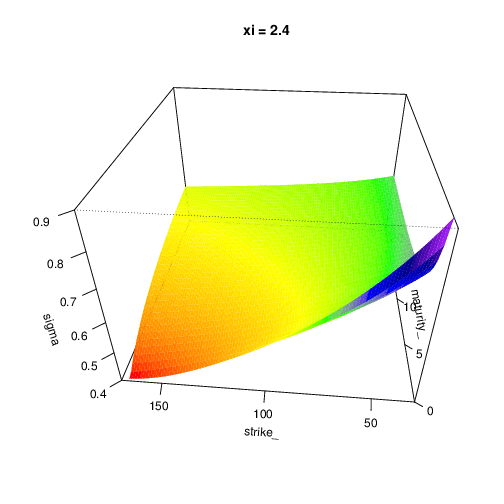
To expose the parameters influence, we expose the implied volatility surface in function of the model parameters.
Don’t hesitate to expand this section
Let’s have the following parameters:
s0 = 100 and r = 0.02
lambda = 0.2
sigma = 0.3
mu_z = -0.3
sigma_z = 0.1
lambda
sigma
sigma_z
mu_z
Bates Model
This model merges the benefits of Merton and Heston models.
The underlying dynamic is based on the Black-Scholes one with two additional features:
Jump part: control the smile for short term smile (< 1 an)
Stochastic volatility part, follow a Cox Ingersoll Ross (CIR) process: control the smile for higher maturities (> 1 an)
General dynamic
Let W s W^s W s W v W^v W v ρ ∈ [ − 1 , 1 ] \rho \in \mathopen{[}-1,1\mathclose{]} ρ ∈ [ − 1 , 1 ]
Let J J J
Let have the filtration ( F t ) = ( σ ( W u s ) u ≤ t ) ∨ ( σ ( W u v ) u ≤ t ) ∨ ( σ ( J u ) u ≤ t ) (\mathcal{F}_t) = ( \sigma(W_u^s)_{u \le t} ) \lor ( \sigma(W_u^v)_{u \le t} ) \lor ( \sigma(J_u)_{u \le t} ) ( F t ) = ( σ ( W u s ) u ≤ t ) ∨ ( σ ( W u v ) u ≤ t ) ∨ ( σ ( J u ) u ≤ t )
The underlying dynamic is the following one:
d S t S t − = ( r t + λ ( 1 − μ a ) ) d t + V t − d W t s + d J t d V t = ξ ( η − V t ) d t + θ V t d W t v
\begin{align*}
\frac{d S_t}{S_{t^{-}}} & = ( r_t + \lambda ( 1 - \mu_a) ) dt + \sqrt{V_{t^{-}}} d W_t^s+ d J_t \\
dV_{t} & = \xi (\eta - V_{t}) dt + \theta \sqrt{V_{t}} d W_t^v
\end{align*}
S t − d S t d V t = ( r t + λ ( 1 − μ a )) d t + V t − d W t s + d J t = ξ ( η − V t ) d t + θ V t d W t v
with
J t = ∑ i = 1 N t ( A i − 1 ) J_t = \displaystyle \sum_{ i = 1}^{N_t} ( A_i - 1 ) J t = i = 1 ∑ N t ( A i − 1 ) ∀ i ∈ N ∗ , ∀ t ∈ R + , A i ⊥ ⊥ N t \forall i \in \mathbb{N}^*, \forall t \in \mathbb{R}^+, A_i \perp\!\!\!\perp N_t ∀ i ∈ N ∗ , ∀ t ∈ R + , A i ⊥ ⊥ N t A i A_i A i ∀ n , ( Z 1 , … , Z n ) ∼ N ( 0 , I n ) \forall n, (Z_1, \ldots ,Z_n ) \sim \mathcal{N}(0, I_n) ∀ n , ( Z 1 , … , Z n ) ∼ N ( 0 , I n ) A i = e μ z + σ z Z i A_i = e^{\mu_z + \sigma_z Z_i } A i = e μ z + σ z Z i μ z ∈ R \mu_z \in \mathbb{R} μ z ∈ R σ z ∈ R + \sigma_z \in \mathbb{R}^+ σ z ∈ R + ( ξ ( \xi ( ξ η \eta η θ ) ∈ R 3 + \theta )\in {\mathbb{R}^3}^+ θ ) ∈ R 3 + μ a = e μ z + σ z 2 2 \mu_a = e^{\mu_z + \frac{\sigma_z^2}{2}} μ a = e μ z + 2 σ z 2
European call price
We expose in this section three different methods to compute a call price in the Bates model:
Monte-Carlo
PIDE
Fourier transform (available for all models with a known characteristic function for the underlying)
For Monte-Carlo and PIDE methods, we refer the reader to the book of R. Cont and P. Tankov:
“Financial Modelling with Jump Processes”.
We develop the Fourier transform in the following section.
We first recall the general Fourier transform pricing then apply it to the Bates model case.
The reader can expand/collapse for more details on Call/Put valuation using Fourier transform method
Let introduce some notations:
C a l l ( t , S , K , T ) Call(t, S, K, T) C a l l ( t , S , K , T ) T T T K K K ∀ t ∈ R + ∗ , S t = C ( t ) e X t \forall t \in \mathbb{R}^{+*}, S_t = C(t) e^{X_t} ∀ t ∈ R +∗ , S t = C ( t ) e X t ∀ t ∈ R ∗ \forall t \in \mathbb{R}^* ∀ t ∈ R ∗ X t X_t X t χ \chi χ
The first step is to rewrite the european call price as follow:
C a l l ( 0 , S , K , t ) = 1 C ( t ) E [ ( S t − K ) + ∣ F 0 ] = S 0 E [ ( e X t − K S 0 C ( t ) ) + ∣ F 0 ] = S 0 E [ ( e X t − e k ) + ∣ F 0 ]
\begin{equation*}
Call(0, S, K, t) = \frac{1}{C(t)} \mathbb{E} [ (S_t - K)_{+} | F_{0}] = S_0 \mathbb{E} [ (e^{X_t} - \frac{K}{S_0 C(t)} )_{+} | F_{0}] = S_0 \mathbb{E} [ (e^{X_t} - e{^k})_{+} | F_{0}]
\end{equation*}
C a l l ( 0 , S , K , t ) = C ( t ) 1 E [( S t − K ) + ∣ F 0 ] = S 0 E [( e X t − S 0 C ( t ) K ) + ∣ F 0 ] = S 0 E [( e X t − e k ) + ∣ F 0 ] with k = l o g ( K S 0 C ( t ) ) k = log ( \frac{K}{S_0 C(t)} ) k = l o g ( S 0 C ( t ) K )
Remark that E [ ( e X t − e k ) + ∣ F 0 ] = E [ ( e X t − e k ( e X t − k ∧ 1 ) ) ∣ F 0 ] \mathbb{E} [ (e^{X_t} - e{^k})_{+} | F_{0}] = \mathbb{E} [ (e^{X_t} - e^{k} ( e^{X_t - k} \land 1) ) | F_{0}] E [( e X t − e k ) + ∣ F 0 ] = E [( e X t − e k ( e X t − k ∧ 1 )) ∣ F 0 ]
Let’s develope the conditional expectation:
E [ ( e X t − e k ( e X t − k ∧ 1 ) ) ∣ F 0 ] = ∫ − ∞ ∞ e x f ( x ) d x − e ( − α + 1 ) k ∫ − ∞ ∞ ( 1 ∧ e − ( k − x ) ) e α ( k − x ) e α x f ( x ) d x
\mathbb{E} [ (e^{X_t} - e^{k} \left( e^{X_t - k} \land 1) \right) | F_{0}]
= \displaystyle \int\limits_{-\infty}^{\infty} e^{x} f(x) dx - e^{(-\alpha + 1) k} \displaystyle \int\limits_{-\infty}^{\infty} ( 1 \land e^{- (k - x) } ) e^{ \alpha (k - x)} e^{ \alpha x} f(x) dx
E [( e X t − e k ( e X t − k ∧ 1 ) ) ∣ F 0 ] = − ∞ ∫ ∞ e x f ( x ) d x − e ( − α + 1 ) k − ∞ ∫ ∞ ( 1 ∧ e − ( k − x ) ) e α ( k − x ) e α x f ( x ) d x
with f ( x ) f(x) f ( x ) X t X_t X t α ∈ [ 0 , 1 ] \alpha \in \mathopen{[}0,1\mathclose{]} α ∈ [ 0 , 1 ]
We have the following result:
E [ ( e X t − e k ) + ∣ F 0 ] = χ ( 1 ) − e ( − α + 1 ) k ∫ − ∞ ∞ ( 1 ∧ e − ( k − x ) ) e α ( k − x ) e α x f ( x ) d x
\mathbb{E} [ (e^{X_t} - e{^k})_{+} | F_{0}] = \chi (1) - e^{(-\alpha + 1)k} \displaystyle \int\limits_{-\infty}^{\infty} ( 1 \land e^{- (k - x) } ) e^{ \alpha (k - x)} e^{ \alpha x} f(x) dx
E [( e X t − e k ) + ∣ F 0 ] = χ ( 1 ) − e ( − α + 1 ) k − ∞ ∫ ∞ ( 1 ∧ e − ( k − x ) ) e α ( k − x ) e α x f ( x ) d x Let’s note: g ( x ) = ( 1 ∧ e − x ) e α x g(x) = ( 1 \land e^{- x} ) e^{ \alpha x} g ( x ) = ( 1 ∧ e − x ) e α x h ( x ) = e α x f ( x ) h(x) = e^{ \alpha x} f(x) h ( x ) = e α x f ( x )
Using the property:
g ∗ h = T F − 1 ( T F ( g ∗ h ) ) = T F − 1 ( T F ( g ) T F ( h ) ) g * h = TF^{-1} ( TF (g * h) ) = TF^{-1} ( TF (g) TF (h) ) g ∗ h = T F − 1 ( T F ( g ∗ h )) = T F − 1 ( T F ( g ) T F ( h ))
We can compute the two followings Fourier transform:
T F ( g ) ( u ) = ∫ − ∞ ∞ e i u x ( 1 ∧ e − x ) e α x = ∫ − ∞ 0 e i u x + α x d x + ∫ 0 ∞ e i u x + x ( α − 1 ) d x = 1 i u + α − 1 i u + α − 1 = − 1 ( i u + α ) ( i u + α − 1 ) T F ( h ) ( u ) = ∫ − ∞ ∞ e i u x e α x f ( x ) d x = χ ( α + i u )
\begin{align*}
TF (g) (u) & = \int\limits_{-\infty}^{\infty} e^{i u x} ( 1 \land e^{- x} ) e^{ \alpha x} \\
& = \int\limits_{-\infty}^{0} e^{i u x + \alpha x} dx + \int\limits_{0}^{\infty} e^{i u x + x (\alpha-1) } dx \\
& = \displaystyle \frac{1}{i u + \alpha} - \frac{1}{i u + \alpha -1} = \frac{-1}{(i u + \alpha) (i u + \alpha -1)} \\
TF (h) (u) & = \int\limits_{-\infty}^{\infty} e^{i u x} e^{ \alpha x} f(x) dx = \chi (\alpha + i u)
\end{align*}
T F ( g ) ( u ) T F ( h ) ( u ) = − ∞ ∫ ∞ e i ux ( 1 ∧ e − x ) e α x = − ∞ ∫ 0 e i ux + α x d x + 0 ∫ ∞ e i ux + x ( α − 1 ) d x = i u + α 1 − i u + α − 1 1 = ( i u + α ) ( i u + α − 1 ) − 1 = − ∞ ∫ ∞ e i ux e α x f ( x ) d x = χ ( α + i u ) Therefore, we have:
g ∗ h = − 1 2 π ∫ − ∞ ∞ e − k i u ( i u + α ) ( i u + α − 1 ) χ ( α + i u ) d u g * h = \frac{- 1}{2 \pi} \displaystyle \int\limits_{-\infty}^{\infty} \frac{e^{-k i u }}{(i u + \alpha) (i u + \alpha -1)} \chi (\alpha + i u) du g ∗ h = 2 π − 1 − ∞ ∫ ∞ ( i u + α ) ( i u + α − 1 ) e − k i u χ ( α + i u ) d u
C a l l ( 0 , S , K , t ) = S 0 χ ( 1 ) + S 0 e k ( − α + 1 ) 2 π ∫ − ∞ ∞ e − k i u ( i u + α ) ( i u + α − 1 ) χ ( α + i u ) d u Call(0, S, K, t) = S_0 \chi(1) + S_0 \displaystyle \frac{ e^{k (-\alpha + 1)}}{2 \pi} \displaystyle
\int\limits_{-\infty}^{\infty} \frac{e^{-k i u }}{(i u + \alpha) (i u + \alpha -1)} \chi (\alpha + i u) du C a l l ( 0 , S , K , t ) = S 0 χ ( 1 ) + S 0 2 π e k ( − α + 1 ) − ∞ ∫ ∞ ( i u + α ) ( i u + α − 1 ) e − k i u χ ( α + i u ) d u Because the function are Hermitian χ ( α + i u ) ‾ = χ ( α − i u ) \overline{\chi (\alpha + iu)} = \chi (\alpha - iu) χ ( α + i u ) = χ ( α − i u ) H H H ∀ x ∈ C \forall x \in \mathbb{C} ∀ x ∈ C H ( x ) ‾ = H ( − x ) \overline{H(x)} = H(-x) H ( x ) = H ( − x )
Let’s rewrite the integral term:
∫ − ∞ + ∞ H ( x ) d x = ∫ − ∞ 0 H ( x ) d x + ∫ 0 + ∞ H ( x ) d x = ∫ 0 + ∞ H ( x ) d x ‾ + ∫ 0 + ∞ H ( x ) d x = 2 R e ( ∫ 0 + ∞ H ( x ) d x ) \displaystyle \int\limits_{-\infty}^{+\infty} H (x) dx = \int\limits_{-\infty}^{0} H (x) dx + \int\limits_{0}^{+\infty} H (x) dx
= \displaystyle \overline{\int\limits_{0}^{+\infty} H (x) dx} + \int\limits_{0}^{+\infty} H (x) dx
= 2 Re ( \int\limits_{0}^{+\infty} H (x) dx ) − ∞ ∫ + ∞ H ( x ) d x = − ∞ ∫ 0 H ( x ) d x + 0 ∫ + ∞ H ( x ) d x = 0 ∫ + ∞ H ( x ) d x + 0 ∫ + ∞ H ( x ) d x = 2 R e ( 0 ∫ + ∞ H ( x ) d x ) We finally have: ∫ − ∞ ∞ H ( x ) d x = 2 R e ∫ 0 ∞ H ( x ) d x \displaystyle \int\limits_{-\infty}^{\infty} H (x) dx = 2 Re \int\limits_{0}^{\infty} H (x) dx − ∞ ∫ ∞ H ( x ) d x = 2 R e 0 ∫ ∞ H ( x ) d x
The price at 0 of an european call on S with maturity t and strike K is:
C a l l ( 0 , S , K , t ) = S 0 χ ( 1 ) + S 0 e k ( − α + 1 ) π ∫ 0 ∞ R e ( e − k i u ( i u + α ) ( i u + α − 1 ) χ ( α + i u ) ) d u = S 0 χ ( 1 ) + ( K C ( t ) ) ( − α + 1 ) S 0 α π ∫ 0 ∞ R e ( e − k i u ( i u + α ) ( i u + α − 1 ) χ ( α + i u ) ) d u
\begin{align*}
Call(0, S, K, t) = & S_0 \chi(1) + S_0 \frac{e^{k(-\alpha + 1)}}{\pi} \displaystyle \int\limits_{0}^{\infty}
Re \left( \frac{e^{-k i u}}{(i u + \alpha) (i u + \alpha -1)} \chi (\alpha + i u) \right) du \\
= & S_0 \chi(1) + \displaystyle \left({\frac{K}{C(t)}}\right)^{(-\alpha + 1)} \frac{S_0^{\alpha}}{\pi} \displaystyle
\int\limits_{0}^{\infty} Re \left( \frac{e^{-k i u}}{(i u + \alpha) (i u + \alpha -1)} \chi (\alpha + i u) \right) du
\end{align*}
C a l l ( 0 , S , K , t ) = = S 0 χ ( 1 ) + S 0 π e k ( − α + 1 ) 0 ∫ ∞ R e ( ( i u + α ) ( i u + α − 1 ) e − k i u χ ( α + i u ) ) d u S 0 χ ( 1 ) + ( C ( t ) K ) ( − α + 1 ) π S 0 α 0 ∫ ∞ R e ( ( i u + α ) ( i u + α − 1 ) e − k i u χ ( α + i u ) ) d u Application in the Bates model
The reader can expand/collapse for more details on Call valuation in Bates model using Fourier transform method
To increase the integral convergence,
we add and remove the call price in another model, for instance in the Merton model noted C M C_{M} C M
C a l l ( 0 , S , K , t ) = C M ( 0 , S , K , t ) + C ( t ) − 1 E [ ( S t − K ) + ∣ F 0 ] − C M ( 0 , S , K , t )
Call(0, S, K, t) = C_{M}(0, S, K, t) + C(t)^{-1} \mathbb{E} [ (S_t - K)_{+} | F_{0}] - C_{M}(0, S, K, t)
C a l l ( 0 , S , K , t ) = C M ( 0 , S , K , t ) + C ( t ) − 1 E [( S t − K ) + ∣ F 0 ] − C M ( 0 , S , K , t ) Simply applying the previously found general formula, we have for C a l l ( 0 , S , K , t ) Call(0, S, K, t) C a l l ( 0 , S , K , t )
C M ( 0 , S , K , t ) + S 0 χ B a t e s ( 1 ) + ( K C ( t ) ) ( − α + 1 ) S 0 α π ∫ 0 ∞ R e ( e − k i u ( i u + α ) ( i u + α − 1 ) χ B a t e s ( α + i u ) ) d u − S 0 χ m ( 1 ) − ( K C ( t ) ) ( − α + 1 ) S 0 α π ∫ 0 ∞ R e ( e − k i u ( i u + α ) ( i u + α − 1 ) χ m ( α + i u ) ) d u = C M ( 0 , S , K , t ) + ( K C ( t ) ) ( − α + 1 ) S 0 α π ∫ 0 ∞ R e [ e − k i u ( i u + α ) ( i u + α − 1 ) ( χ B a t e s ( α + i u ) − χ m ( α + i u ) ) ] d u
\begin{align*}
& C_{M}(0, S, K, t) \\
& + S_0 \chi_{Bates}(1) + \left({\frac{K}{C(t)}}\right)^{(-\alpha + 1)} \frac{S_0^{\alpha} }{\pi} \displaystyle \int\limits_{0}^{\infty}
Re \left( \frac{e^{-k i u}}{(i u + \alpha) (i u + \alpha -1)} \chi_{Bates} (\alpha + i u) \right) du \\
& - S_0 \chi_{m}(1) - \left({\frac{K}{C(t)}}\right)^{(-\alpha + 1)} \frac{S_0^{\alpha} }{\pi} \displaystyle
\int\limits_{0}^{\infty} Re \left( \frac{e^{-k i u}}{(i u + \alpha) (i u + \alpha -1)} \chi_{m} (\alpha + i u) \right) du \\
= & C_{M}(0, S, K, t) \\
& + \left({\frac{K}{C(t)}}\right)^{(-\alpha + 1)} \frac{S_0^{\alpha} }{\pi} \displaystyle \int\limits_{0}^{\infty} Re \left[ \frac{e^{-k i u}}{(i u + \alpha) (i u + \alpha -1)}
( \chi_{Bates} (\alpha + i u) - \chi_{m}(\alpha + i u) ) \right] du
\end{align*}
= C M ( 0 , S , K , t ) + S 0 χ B a t es ( 1 ) + ( C ( t ) K ) ( − α + 1 ) π S 0 α 0 ∫ ∞ R e ( ( i u + α ) ( i u + α − 1 ) e − k i u χ B a t es ( α + i u ) ) d u − S 0 χ m ( 1 ) − ( C ( t ) K ) ( − α + 1 ) π S 0 α 0 ∫ ∞ R e ( ( i u + α ) ( i u + α − 1 ) e − k i u χ m ( α + i u ) ) d u C M ( 0 , S , K , t ) + ( C ( t ) K ) ( − α + 1 ) π S 0 α 0 ∫ ∞ R e [ ( i u + α ) ( i u + α − 1 ) e − k i u ( χ B a t es ( α + i u ) − χ m ( α + i u )) ] d u The first term is computed using the series expansion found in the section dedicated to the Merton model.
Expression of χ B a t e s ( u ) \chi_{Bates}(u) χ B a t es ( u ) χ m ( u ) \chi_{m}(u) χ m ( u ) ∀ u ∈ C \forall u \in \mathbb{C} ∀ u ∈ C
Computation of χ m ( u ) \chi_{m}(u) χ m ( u ) ∀ u ∈ C \forall u \in \mathbb{C} ∀ u ∈ C
∀ u ∈ C , χ m ( u ) = χ m d ( u ) × χ m c ( u ) ∀ u ∈ C , χ m c ( u ) = χ m c ( u ) = χ B S ( u ) = e − σ 2 t 2 ( u − u 2 ) ∀ u ∈ C , χ m d ( u ) = E [ e J t ] = e λ t ( χ a ( u ) − 1 ) = e λ t ( e u ( μ z + u σ z 2 2 ) − 1 )
\begin{align*}
\forall u \in \mathbb{C}, \chi_m(u) & = \chi_m^d(u) \times \chi_m^c(u) \\
\forall u \in \mathbb{C}, \chi_m^c(u) & = \chi_m^c(u) = \chi_{BS}(u) = e^{ - \frac{\sigma^2 t}{2}(u-u^2)} \\
\forall u \in \mathbb{C}, \chi_{m}^d(u) & = \mathbb{E} [ e^{J_t} ] = e^{ \lambda t ( \chi_a(u) - 1 )} \\
& = \displaystyle e^{ \lambda t \left( e^{u ( \mu_z + \frac{u \sigma_z^2}{2} )} - 1 \right)}
\end{align*}
∀ u ∈ C , χ m ( u ) ∀ u ∈ C , χ m c ( u ) ∀ u ∈ C , χ m d ( u ) = χ m d ( u ) × χ m c ( u ) = χ m c ( u ) = χ B S ( u ) = e − 2 σ 2 t ( u − u 2 ) = E [ e J t ] = e λ t ( χ a ( u ) − 1 ) = e λ t ( e u ( μ z + 2 u σ z 2 ) − 1 )
With χ a \chi_a χ a A i A_i A i
We note ∀ u ∈ C \forall u \in \mathbb{C} ∀ u ∈ C χ m d ( u ) = χ J u m p ( u ) \displaystyle \chi_{m}^d(u) = \chi_{Jump}(u) χ m d ( u ) = χ J u m p ( u )
Computation of χ B a t e s ( u ) \chi_{Bates}(u) χ B a t es ( u ) ∀ u ∈ C \forall u \in \mathbb{C} ∀ u ∈ C
∀ u ∈ C , χ B a t e s ( u ) = χ B a t e s c ( u ) × χ B a t e s d ( u ) ∀ u ∈ C , χ B a t e s d ( u ) = χ J u m p ( u ) = E [ e J t ] = e x p ( λ T ( e u μ z + u 2 σ z 2 2 − 1 ) ) ∀ u ∈ C , χ B a t e s c ( u ) = χ H e s t o n ( u )
\begin{align*}
\forall u \in \mathbb{C}, \chi_{Bates}(u) & = \chi_{Bates}^c(u) \times \chi_{Bates}^d(u) \\
\forall u \in \mathbb{C},\chi_{Bates}^d(u) & = \chi_{Jump}(u) = \mathbb{E} [ e^{J_t} ] = exp\left(\lambda T( e^{u \mu_z + u^2 \frac{\sigma_z^2 }{2} } - 1)\right) \\
\forall u \in \mathbb{C}, \chi_{Bates}^c(u) & = \chi_{Heston}(u)
\end{align*}
∀ u ∈ C , χ B a t es ( u ) ∀ u ∈ C , χ B a t es d ( u ) ∀ u ∈ C , χ B a t es c ( u ) = χ B a t es c ( u ) × χ B a t es d ( u ) = χ J u m p ( u ) = E [ e J t ] = e x p ( λ T ( e u μ z + u 2 2 σ z 2 − 1 ) ) = χ H es t o n ( u ) First of all, let’s note X = l o g ( S ) X = log(S) X = l o g ( S ) l o g ( S ) log(S) l o g ( S )
d X t = ( r t + λ ( 1 − m u a ) − 1 2 V t ) d t + V t d W t s dX_t = (r_t + \lambda(1 - mu_a) - \frac{1}{2}V_t )dt + \sqrt{V_t} dW_t^s d X t = ( r t + λ ( 1 − m u a ) − 2 1 V t ) d t + V t d W t s Let’s note ∀ t ∈ R + \forall t \in \mathbb{R}^{+} ∀ t ∈ R + M t = f ( X t c , V t , t ) M_t = f(X_t^c, V_t, t ) M t = f ( X t c , V t , t ) ∀ ( x , v , t ) ∈ ( R + ) 3 \forall (x,v,t) \in (\mathbb{R}^{+})^3 ∀ ( x , v , t ) ∈ ( R + ) 3 f ( x , v , t ) = E [ e u X t c ∣ X t c = x , V t = v ] f(x, v, t ) = \mathbb{E} [ e^{u X_t^c} |X_t^c = x , V_t = v ] f ( x , v , t ) = E [ e u X t c ∣ X t c = x , V t = v ]
For the sake of clarity, let’s introduce f = f ( X t c , V t , t ) f = f(X_t^c, V_t, t) f = f ( X t c , V t , t ) M t M_t M t
d M t = ∂ f ∂ x d X t c + ∂ f ∂ v d V t + ∂ f ∂ t d t + 1 2 [ ∂ 2 f ∂ x 2 d [ X c ] t + ∂ 2 f ∂ v 2 d [ V ] t + 2 ∂ 2 f ∂ x ∂ v d [ X c , V ] t ]
d M_t = \displaystyle \frac{\partial f }{\partial x } d X_t^c + \frac{\partial f }{\partial v } d V_t + \frac{\partial f }{\partial t } d t + \frac{1}{2} \left[ \frac{\partial^2 f }{\partial x^2 } d[ X^c ]_t + \frac{\partial^2 f }{\partial v^2 } d[ V ]_t + 2 \frac{\partial^2 f }{\partial x \partial v } d[ X^c , V ]_t \right]
d M t = ∂ x ∂ f d X t c + ∂ v ∂ f d V t + ∂ t ∂ f d t + 2 1 [ ∂ x 2 ∂ 2 f d [ X c ] t + ∂ v 2 ∂ 2 f d [ V ] t + 2 ∂ x ∂ v ∂ 2 f d [ X c , V ] t ] Let’s compute each terms:
d X t c = ( r t + λ ( 1 − μ A ) − V t 2 ) d t + V t d W t s d V t = ξ ( η − V t ) d t + θ V t d W t v d [ X c ] t = V t d t d [ V ] t = θ 2 V t d t d [ X c , V ] t = ρ θ V t d t
\begin{align*}
d X_t^c & = \displaystyle (r_t + \lambda (1 - \mu_A) - \frac{V_t}{2}) dt + \sqrt{V_t} d W_t^s \\
d V_t & = \xi (\eta - V_{t}) dt + \theta \sqrt{V_{t}} d W_t^v \\
d[ X^c ]_t & = V_t dt \\
d[ V ]_t & = \theta^2 V_t dt \\
d[ X^c , V ]_t & = \rho \theta V_t dt
\end{align*}
d X t c d V t d [ X c ] t d [ V ] t d [ X c , V ] t = ( r t + λ ( 1 − μ A ) − 2 V t ) d t + V t d W t s = ξ ( η − V t ) d t + θ V t d W t v = V t d t = θ 2 V t d t = ρθ V t d t Substituting, we have:
d M t = ∂ f ∂ x ( ( r t + λ ( 1 − μ A ) − V t 2 ) d t + V t d W t s ) + ∂ f ∂ v ( ξ ( η − V t ) d t + θ V t d W t v ) + ∂ f ∂ t d t + 1 2 [ ∂ 2 f ∂ x 2 V t + ∂ 2 f ∂ v 2 θ 2 V t + 2 ∂ 2 f ∂ x ∂ v ρ θ V t ] d t = [ ∂ f ∂ x ( r t + λ ( 1 − μ A ) − V t 2 ) + ∂ f ∂ v ξ ( η − V t ) + ∂ f ∂ t + 1 2 ∂ 2 f ∂ x 2 V t + 1 2 ∂ 2 f ∂ v 2 θ 2 V t + ∂ 2 f ∂ x ∂ v ρ θ V t ] d t + θ V t d W t v + V t d W t s
\begin{align*}
d M_t = & \displaystyle \frac{\partial f }{\partial x } ( (r_t + \lambda (1 - \mu_A) - \frac{V_t}{2}) dt + \sqrt{V_t} d W_t^s ) + \frac{\partial f }{\partial v } ( \xi (\eta - V_{t}) dt + \theta \sqrt{V_{t}} d W_t^v ) + \frac{\partial f }{\partial t } d t \\
& \displaystyle + \frac{1}{2} [ \frac{\partial^2 f }{\partial x^2 } V_t + \frac{\partial^2 f }{\partial v^2 } \theta^2 V_t + 2 \frac{\partial^2 f }{\partial x \partial v } \rho \theta V_t ] dt \\
= & [ \displaystyle \frac{\partial f }{\partial x } (r_t + \lambda (1 - \mu_A) - \frac{V_t}{2}) + \frac{\partial f }{\partial v } \xi (\eta - V_{t}) + \frac{\partial f }{\partial t } \\
& + \frac{1}{2}\frac{\partial^2 f }{\partial x^2 } V_t + \frac{1}{2}\frac{\partial^2 f }{\partial v^2 } \theta^2 V_t + \frac{\partial^2 f }{\partial x \partial v } \rho \theta V_t ] dt + \displaystyle \theta \sqrt{V_{t}} d W_t^v + \sqrt{V_{t}} d W_t^s
\end{align*}
d M t = = ∂ x ∂ f (( r t + λ ( 1 − μ A ) − 2 V t ) d t + V t d W t s ) + ∂ v ∂ f ( ξ ( η − V t ) d t + θ V t d W t v ) + ∂ t ∂ f d t + 2 1 [ ∂ x 2 ∂ 2 f V t + ∂ v 2 ∂ 2 f θ 2 V t + 2 ∂ x ∂ v ∂ 2 f ρθ V t ] d t [ ∂ x ∂ f ( r t + λ ( 1 − μ A ) − 2 V t ) + ∂ v ∂ f ξ ( η − V t ) + ∂ t ∂ f + 2 1 ∂ x 2 ∂ 2 f V t + 2 1 ∂ v 2 ∂ 2 f θ 2 V t + ∂ x ∂ v ∂ 2 f ρθ V t ] d t + θ V t d W t v + V t d W t s Moreover, we know that f ( X ⋅ c , V ⋅ , ⋅ ) f(X_{\cdot}^c, V_{\cdot}, \cdot) f ( X ⋅ c , V ⋅ , ⋅ ) f ( X ⋅ c , V ⋅ , ⋅ ) f(X_{\cdot}^c, V_{\cdot}, \cdot) f ( X ⋅ c , V ⋅ , ⋅ )
∂ f ∂ x ( r t + λ ( 1 − μ A ) − V t 2 ) + ∂ f ∂ v ξ ( η − V t ) + ∂ f ∂ t + 1 2 ∂ 2 f ∂ x 2 V t + 1 2 ∂ 2 f ∂ v 2 θ 2 V t + ∂ 2 f ∂ x ∂ v ρ θ V t = 0
\displaystyle \frac{\partial f }{\partial x } (r_t + \lambda (1 - \mu_A) - \frac{V_t}{2}) + \frac{\partial f }{\partial v } \xi (\eta - V_{t}) + \frac{\partial f }{\partial t } + \frac{1}{2}\frac{\partial^2 f }{\partial x^2 } V_t + \frac{1}{2}\frac{\partial^2 f }{\partial v^2 } \theta^2 V_t + \frac{\partial^2 f }{\partial x \partial v} \rho \theta V_t = 0
∂ x ∂ f ( r t + λ ( 1 − μ A ) − 2 V t ) + ∂ v ∂ f ξ ( η − V t ) + ∂ t ∂ f + 2 1 ∂ x 2 ∂ 2 f V t + 2 1 ∂ v 2 ∂ 2 f θ 2 V t + ∂ x ∂ v ∂ 2 f ρθ V t = 0
with the terminal condition f ( x , v , t ) = e u x f(x,v,t) = e^{ux} f ( x , v , t ) = e ux
We suppose the solution can be written as follow: f ( x , v , t ) = e A ( T − t ) + v B ( T − t ) + u x f(x, v, t) = e^{ A(T-t) + v B(T-t) + u x } f ( x , v , t ) = e A ( T − t ) + v B ( T − t ) + ux A ( 0 ) = 0 A(0) = 0 A ( 0 ) = 0 B ( 0 ) = 0 B(0) = 0 B ( 0 ) = 0
∂ f ∂ x = u f ∂ f ∂ v = B ( T − t ) f ∂ f ∂ t = − ∂ A ∂ t ( T − t ) + − V t ∂ B ∂ t ( T − t ) ∂ 2 f ∂ x 2 = u 2 f ∂ 2 f ∂ v 2 = B ( T − t ) 2 f ∂ 2 f ∂ x ∂ v = − u B ( T − t ) f
\begin{align*}
\displaystyle \frac{\partial f }{\partial x } & = u f \\
\frac{\partial f }{\partial v } & = B(T-t) f \\
\frac{\partial f }{\partial t } & = - \frac{\partial A }{\partial t }(T-t) + -V_t \frac{\partial B }{\partial t }(T-t) \\
\frac{\partial^2 f }{\partial x^2 } & = u^2 f \\
\displaystyle \frac{\partial^2 f }{\partial v^2 } & = B(T-t)^2 f \\
\frac{\partial^2 f }{\partial x \partial v } & = - u B(T-t) f
\end{align*}
∂ x ∂ f ∂ v ∂ f ∂ t ∂ f ∂ x 2 ∂ 2 f ∂ v 2 ∂ 2 f ∂ x ∂ v ∂ 2 f = u f = B ( T − t ) f = − ∂ t ∂ A ( T − t ) + − V t ∂ t ∂ B ( T − t ) = u 2 f = B ( T − t ) 2 f = − u B ( T − t ) f The equation can be written by substituting:
u f ( r t + λ ( 1 − μ A ) − V t 2 ) + B ( t ) f ξ ( η − V t ) − ( ∂ A ∂ t ( t ) + V t ∂ B ∂ t ( t ) ) + 1 2 u 2 f V t + 1 2 B ( t ) 2 f θ 2 V t − u B ( t ) f ρ θ V t = 0
\begin{align*}
& \displaystyle u f (r_t + \lambda (1 - \mu_A) - \frac{V_t}{2}) + B(t) f \xi (\eta - V_{t}) - (\frac{\partial A }{\partial t }(t) + V_t \frac{\partial B }{\partial t }(t) ) \\
& + \frac{1}{2}u^2 f V_t + \frac{1}{2}B(t)^2 f \theta^2 V_t - u B(t) f \rho \theta V_t = 0
\end{align*}
u f ( r t + λ ( 1 − μ A ) − 2 V t ) + B ( t ) f ξ ( η − V t ) − ( ∂ t ∂ A ( t ) + V t ∂ t ∂ B ( t )) + 2 1 u 2 f V t + 2 1 B ( t ) 2 f θ 2 V t − u B ( t ) f ρθ V t = 0 u ( r t + λ ( 1 − μ A ) ) + B ( t ) ξ η − ∂ A ∂ t ( t ) + [ − ∂ B ∂ t ( t ) − B ( t ) ξ + 1 2 u 2 + 1 2 B ( t ) 2 θ 2 − u B ( t ) ρ θ − u 2 ] V t = 0
\begin{align*}
& \displaystyle u(r_t + \lambda (1 - \mu_A)) + B(t)\xi \eta - \frac{\partial A }{\partial t }(t) \\
& + \left[ - \frac{\partial B }{\partial t }(t) - B(t)\xi + \frac{1}{2}u^2 + \frac{1}{2}B(t)^2 \theta^2 - u B(t) \rho \theta - \frac{u}{2} \right] V_t = 0
\end{align*}
u ( r t + λ ( 1 − μ A )) + B ( t ) ξ η − ∂ t ∂ A ( t ) + [ − ∂ t ∂ B ( t ) − B ( t ) ξ + 2 1 u 2 + 2 1 B ( t ) 2 θ 2 − u B ( t ) ρθ − 2 u ] V t = 0 The two solutions of our problem are:
∂ A ∂ t ( t ) = B ( t ) ξ η + u ( r t + λ ( 1 − μ A ) ) ∂ B ∂ t ( t ) = 1 2 θ 2 B ( t ) 2 − ξ B ( t ) − ρ θ u B ( t ) + 1 2 u 2 − 1 2 u = 1 2 θ 2 B ( t ) 2 − ( ρ θ u + ξ ) B ( t ) − u 2 ( 1 − u )
\begin{align*}
\displaystyle \frac{\partial A }{\partial t }(t) & = B(t) \xi \eta + u (r_t + \lambda (1 - \mu_A)) \\
\displaystyle \frac{\partial B }{\partial t }(t) & = \frac{1}{2}\theta^2 B(t)^2 - \xi B(t) - \rho \theta u B(t) + \frac{1}{2}u^2 - \frac{1}{2}u
= \frac{1}{2}\theta^2 B(t)^2 - ( \rho \theta u + \xi ) B(t) - \frac{u}{2}( 1 - u )
\end{align*}
∂ t ∂ A ( t ) ∂ t ∂ B ( t ) = B ( t ) ξ η + u ( r t + λ ( 1 − μ A )) = 2 1 θ 2 B ( t ) 2 − ξ B ( t ) − ρθ u B ( t ) + 2 1 u 2 − 2 1 u = 2 1 θ 2 B ( t ) 2 − ( ρθ u + ξ ) B ( t ) − 2 u ( 1 − u ) The first one is an integral computation. The second one is a Riccati equation.
The solutions of our two equations can be written as follow:
A ( t ) = u ( 1 l o g ( C ( t ) ) + t λ ( 1 − μ A ) ) + ξ η t ( ξ + ρ θ u ) θ 2 − 2 ξ η θ 2 l o g ( c o s h ( γ t 2 ) − ξ + ρ θ u γ s i n ( γ t 2 ) ) B ( t ) = − u − u 2 γ c o t h ( γ t 2 ) − ξ − ρ θ u
\begin{align*}
\displaystyle A(t) & = u \left( \frac{1}{log ( C(t))} + t \lambda ( 1 - \mu_A) \right) + \frac{\xi \eta t (\xi + \rho \theta u)}{\theta^2} - \frac{2 \xi \eta}{\theta^2} log \left( cosh ( \frac{\gamma t}{2} ) - \frac{\xi + \rho \theta u}{\gamma} sin ( \frac{\gamma t}{2} ) \right) \\
\displaystyle B(t) & = - \frac{u - u^2}{\gamma coth ( \frac{\gamma t}{2} ) - \xi - \rho \theta u }
\end{align*}
A ( t ) B ( t ) = u ( l o g ( C ( t )) 1 + t λ ( 1 − μ A ) ) + θ 2 ξ η t ( ξ + ρθ u ) − θ 2 2 ξ η l o g ( cos h ( 2 γ t ) − γ ξ + ρθ u s in ( 2 γ t ) ) = − γ co t h ( 2 γ t ) − ξ − ρθ u u − u 2
with γ = θ 2 ( u − u 2 ) + ( ξ + ρ θ u ) 2 \gamma = \displaystyle \sqrt{\theta^2 (u - u^2) + (\xi + \rho \theta u)^2} γ = θ 2 ( u − u 2 ) + ( ξ + ρθ u ) 2
We have the log characteristic function:
l o g ( χ B a t e s c ( u ) ) = u ( 1 l o g ( C ( t ) ) + t λ ( 1 − μ A ) ) + ξ η t ( ξ + ρ θ u ) θ 2 − 2 ξ η θ 2 l o g ( c o s h ( γ t 2 ) − ξ + ρ θ u γ s i n ( γ t 2 ) ) − V 0 u − u 2 γ c o t h ( γ t 2 ) − ξ − ρ θ u + u X 0
\begin{align*}
log(\chi_{Bates}^c(u)) &= u \left( \frac{1}{log ( C(t) )} + t \lambda ( 1 - \mu_A)\right) + \frac{\xi \eta t (\xi + \rho \theta u)}{\theta^2}\\
&- \frac{2 \xi \eta}{\theta^2} log \left(cosh ( \frac{\gamma t}{2}) - \frac{\xi + \rho \theta u}{\gamma} sin ( \frac{\gamma t}{2} ) \right) - V_0 \frac{u - u^2}{\gamma coth ( \frac{\gamma t}{2} ) - \xi - \rho \theta u } + u X_0
\end{align*}
l o g ( χ B a t es c ( u )) = u ( l o g ( C ( t )) 1 + t λ ( 1 − μ A ) ) + θ 2 ξ η t ( ξ + ρθ u ) − θ 2 2 ξ η l o g ( cos h ( 2 γ t ) − γ ξ + ρθ u s in ( 2 γ t ) ) − V 0 γ co t h ( 2 γ t ) − ξ − ρθ u u − u 2 + u X 0 and the call price in the Bates model is given by:
C a l l ( 0 , S , K , t ) = C M ( 0 , S , K , t ) − K π C ( t ) ∫ 0 ∞ R e [ e − k ( α + i u ) χ J ( α + i u ) ( i u + α ) ( i u + α − 1 ) ( χ H e s t o n ( α + i u ) − χ B S ( α + i u ) ) ] d u
\begin{align*}
Call(0, S, K, t) &= C_M(0, S, K, t)\\
& - \frac{K}{\pi C(t)} \displaystyle \int\limits_{0}^{\infty} Re \left[ \frac{e^{-k( \alpha + i u )} \chi_J (\alpha + i u) }{(i u + \alpha) (i u + \alpha -1)} \left( \chi_{Heston}(\alpha + i u) - \chi_{BS}(\alpha + i u) \right) \right] du
\end{align*}
C a l l ( 0 , S , K , t ) = C M ( 0 , S , K , t ) − π C ( t ) K 0 ∫ ∞ R e [ ( i u + α ) ( i u + α − 1 ) e − k ( α + i u ) χ J ( α + i u ) ( χ H es t o n ( α + i u ) − χ B S ( α + i u ) ) ] d u Control variate choice
To compute the Bates’ call price, we can choose the Merton, Black-Scholes, or no control variate to increase the accuracy.
Remark:
Using a Black-Scholes or Merton call price as control variate, we have to choose the volatility σ \sigma σ
Let’s identify σ \sigma σ θ = 0 \theta = 0 θ = 0 ∀ t ∈ R + ∗ \forall t \in \mathbb{R}^{+*} ∀ t ∈ R +∗ d ( e ξ t V t ) = V t ξ e ξ t d t + e ξ t d V t = V t ξ e ξ t d t + e ξ t ξ ( η − V t ) d t = e ξ t ξ η d t e ξ t V t − V 0 = ∫ 0 t e ξ t ξ η d t ⟺ V t = e − ξ t ( V 0 − η ) + η \begin{align*} \displaystyle d( e^{\xi t} V_t ) & = V_t \xi e^{\xi t} dt + e^{\xi t} dV_t = V_t \xi e^{\xi t} dt + e^{\xi t} \xi (\eta - V_{t}) dt =e^{\xi t} \xi \eta dt \\ \displaystyle e^{\xi t} V_t - V_0 & = \int\limits_0^t e^{\xi t} \xi \eta dt \iff V_t = e^{-\xi t} (V_0 - \eta) + \eta \end{align*} d ( e ξ t V t ) e ξ t V t − V 0 = V t ξ e ξ t d t + e ξ t d V t = V t ξ e ξ t d t + e ξ t ξ ( η − V t ) d t = e ξ t ξ η d t = 0 ∫ t e ξ t ξ η d t ⟺ V t = e − ξ t ( V 0 − η ) + η
σ \sigma σ σ = e − ξ t ( V 0 − η ) + η \sigma = \displaystyle \sqrt{e^{-\xi t} (V_0 - \eta) + \eta} σ = e − ξ t ( V 0 − η ) + η σ \sigma σ σ 2 = ∫ 0 t V s d s = 1 t [ ( e − ξ t − 1 ) ( η − V 0 ) ξ + η t ] ⟺ σ = ( e − ξ t − 1 ) ( η − V 0 ) ξ t + η \sigma^2 = \displaystyle \int\limits_0^t V_s ds = \frac{1}{t} [ \frac{(e^{-\xi t} - 1)(\eta - V_0)}{\xi} +\eta t ] \iff \sigma = \sqrt{\frac{(e^{-\xi t} - 1)(\eta - V_0)}{\xi t} +\eta} σ 2 = 0 ∫ t V s d s = t 1 [ ξ ( e − ξ t − 1 ) ( η − V 0 ) + η t ] ⟺ σ = ξ t ( e − ξ t − 1 ) ( η − V 0 ) + η
Calibration methods
We develop two calibration methods for the Bates model:
In one step and using weight functions
In two steps: Firstly a set of parameters is found using Merton and Heston calibration and secondly a local optimisation is performed
One step method
We minimise the imply/model volatilities in L 2 L^2 L 2
Weight function for strikes:
∀ x ∈ R + ∗ , \forall x \in \mathbb{R}^{+*}, ∀ x ∈ R +∗ , f ( x ) = e − ( ( x − μ ) σ ) 2 σ 2 π f(x) = \displaystyle \frac{ e^{ - \left( \frac{(x - \mu)}{\sigma} \right)^2 }}{\sigma \sqrt{2 \pi}} f ( x ) = σ 2 π e − ( σ ( x − μ ) ) 2 μ = S 0 C ( t ) \mu = S_0 C(t) μ = S 0 C ( t ) σ = s c a l e × 1 2 ( k m i n 2 + k m a x 2 ) − 1 4 ( k m i n + k m a x ) 2 \sigma = scale \times \sqrt{ \frac{1}{2}(k_{min}^2 + k_{max}^2) - \frac{1}{4} (k_{min} + k_{max} )^2 } σ = sc a l e × 2 1 ( k min 2 + k ma x 2 ) − 4 1 ( k min + k ma x ) 2
k m i n k_{min} k min k m a x k_{max} k ma x T ∈ R + ∗ T \in \mathbb{R}^{+*} T ∈ R +∗ s c a l e ∈ R + ∗ scale \in \mathbb{R}^{+*} sc a l e ∈ R +∗
Weight function for maturities:
∀ x ∈ R + ∗ , \forall x \in \mathbb{R}^{+*}, ∀ x ∈ R +∗ , f ( x ) = ( x x 0 ) p x 0 e p ( x − x 0 ) f(x) = \displaystyle (\frac{x}{x_0})^{p x_0} e^{ p(x-x_0) } f ( x ) = ( x 0 x ) p x 0 e p ( x − x 0 ) x 0 x_0 x 0 p p p
Two steps method
We inspect a first solution in the set of Bates parameters.
For the height parameters, we have:
For λ \lambda λ μ z \mu_z μ z σ z \sigma_z σ z σ \sigma σ
We calibrate those parameters in the Merton model for maturities lower than one year. Remark that σ \sigma σ
For V 0 V_0 V 0 ξ \xi ξ ν \nu ν θ \theta θ ρ \rho ρ
We calibrate those parameters in the Heston model for maturities greater than one year. Remark that v 0 v_0 v 0 σ 2 \sigma^2 σ 2
The second step use the previously found parameters as initial solution for a local minimisation.
Parameters impact
To expose the parameters influence, we expose the implied volatility surface in function of the model parameters.
Don’t hesitate to expand this section
Let’s have the following parameters:
s0 = 100
r = 0.2
lambda = 0.5
v0 = 0.4
mu_z = -0.2
sigma_z = 0.2
kappa = 0.5
theta = 0.4
xi = 0.9
rho = -0.7
xi
theta
kappa
rho
Conclusion
We presented in this post some theoretical aspects on discontinuous processes.
We also exposed a generic formulation for jump diffusion model using Lévy process.
We investigated two specific models: Merton and Bates models.
The dynamic, call pricing, calibration and influence of parameters are exposed for each models.
Numerical experiments are provided.
This methodology has been chosen to be implemented in LexiFi Apropos